Key Takeaways
- Treat the negotiation as two separate events: price and structure at the letter of intent, then risk allocation across the definitive agreement and disclosure schedules.
- Settle everything you care about before granting exclusivity, because that is the moment your alternatives disappear and the other side knows it.
- Check whether the deal will carry warranty insurance before you negotiate indemnity caps, since insurance moves that entire argument to the insurer and changes what is worth fighting for.
- Argue the working capital peg, the survival period and the earnout mechanics as hard as the headline number, because each one can move more cash than a percentage point of price.
- Push back hard on any earnout that lacks an operating covenant, since the buyer controls the business that determines whether you get paid.
- Know where the market sits on each term before you open, because “that is not market” is the argument that wins most deal points.
Table of Contents
ToggleM&A negotiation is the process of agreeing price and allocating risk between a buyer and a seller, across a letter of intent and then a definitive agreement. Price usually settles early. The terms that decide how much of that price is actually received, and who pays if something turns out to be wrong, are negotiated for weeks afterwards.
A deal can be agreed at a number both sides are happy with and still deliver a materially different outcome depending on how the definitive agreement is drafted. The seller who conceded a broad indemnity, a twenty-four month survival period and a ten percent escrow has given back several points of price without the price changing.
This piece covers what gets negotiated, how the process runs from first contact to signing, how to prepare, the tactics that work in this specific setting rather than in negotiation generally, the terms that move the most money, where the market currently sits on each one, and what to lock down before you grant exclusivity.
What Gets Negotiated in an M&A Deal
Both sides are trying to get the best outcome, and the outcome is not a single number. An M&A negotiation covers price, the mechanism that adjusts that price, what the seller promises about the business, what happens if those promises turn out to be wrong, how long the buyer can bring a claim, and what has to be true before either side is obliged to close.
It also runs in two distinct phases, and confusing them is expensive. The letter of intent or term sheet settles price, structure, and exclusivity in principle. The definitive agreement settles risk allocation in detail, informed by whatever diligence has turned up. Deal points that were left vague in the letter of intent get resolved in the second phase, when the seller has far less room to move.
Structure belongs in the first phase for the same reason. Whether the deal is a merger, a stock purchase, or an asset purchase agreement changes the tax outcome for both sides and which liabilities transfer, so it is a price term rather than a legal detail. The choice between the available deal structures should be settled before anyone starts drafting.
How the Negotiation Runs, Stage by Stage
Five stages, and the useful way to read them is by who holds the stronger position at each one.
| Stage | What gets decided | Who holds the stronger position |
|---|---|---|
| Preparation and first contact | Whether there is a deal to discuss, and on roughly what basis | Whoever has prepared and has alternatives |
| Indication of interest to letter of intent | Price, structure, exclusivity, and the broad shape of the deal | The seller, if more than one party is interested |
| Diligence | What the buyer believes about the business, and what it will reprice | The buyer, as findings accumulate |
| Definitive agreement markup | Reps and warranties, indemnity, survival, escrow, closing conditions | The buyer, because exclusivity has removed the seller’s alternatives |
| Final open issues | The last handful of points, usually traded against each other | Whichever side is more willing to walk |
Table 1: The five stages of an M&A negotiation and where the advantage sits in each.
The pattern is worth sitting with. A seller’s position is strongest before exclusivity and weakest during the definitive agreement markup, which is exactly when the most consequential terms get drafted. That asymmetry is not a flaw in the process. It is the process, and the only defence is to move as much as possible into the earlier phase.
How to Prepare Before the First Conversation
Preparation decides more of the outcome than technique does, and it comes down to five things.
- Know your walk-away number and write it down. Not a hoped-for price, a floor. Model it net of fees, escrow, and tax, because a gross number tells you nothing about what you receive.
- Build a real alternative. A second interested party, a funding round in progress, or a credible decision to keep operating. Without one, every concession is a one-way conversation.
- Anchor the price on evidence. Comparable transactions give you a defensible range. Precedent transaction analysis is what turns your number from an aspiration into a position.
- Find your own problems first. Whatever the buyer will discover in diligence, you want to have found and either fixed or framed. A surprise reprices the deal; a disclosed issue with a plan attached usually does not.
- Assemble the advisers before you need them. Transaction counsel, a tax adviser, and a banker or broker if the deal warrants one. Bringing counsel in after the letter of intent is signed means negotiating the definitive agreement from a position someone else defined.
Research the counterparty as seriously as your own numbers. How many deals have they closed, what did they pay, do they retain management, do they renegotiate after diligence. A buyer with a pattern of chipping price post-LOI is a different counterparty from one that does not, and you should price the risk accordingly.
Tactics That Work in M&A Specifically
General negotiation advice travels badly into a deal that runs for months with lawyers on both sides. These eight are the ones that behave differently here.
- Anchor first when you have evidence. Naming a number first sets the range, and it works when the number is supported by comparables. Anchoring without support invites the other side to reset the conversation on their terms.
- Trade concessions, never donate them. Every point you give should buy a named point back in the same conversation. Concede the survival period and take the escrow percentage; concede the cap and take a tighter definition of material adverse effect.
- Break one concession into several. Movement matters more than magnitude in the middle of a negotiation. Three small steps read as good faith where one large step reads as a number that was never real.
- Use information asymmetry while you still have it. A seller knows the business; the buyer is inferring. That advantage decays through diligence, which is why the terms you want are the ones you secure early.
- Keep the walk-away credible. A floor only works if the other side believes it, and nothing destroys that belief faster than conceding past a number you announced. If you name one, hold it.
- Ignore sunk cost. Months of work and fees already spent are not a reason to accept worse terms. The question is always whether the deal in front of you beats the alternative from here.
- Argue from market, not from preference. “That is not market” beats “we would prefer not to.” It converts a wish into a benchmark, and it is why the deal points data in the next section is worth knowing before you open.
- Let the advisers hold the friction. Principals who fight directly damage a relationship they will need through integration. Counsel and bankers can take hard positions and still leave the parties able to work together afterwards, which matters most where management is staying on.
The Terms That Move More Money Than Price
Price gets the attention because it is the one number everyone understands. Several other terms move more cash, and they are the ones a prepared negotiator spends time on.
| Term | What is negotiated | Why it moves more than price |
|---|---|---|
| Working capital adjustment | The peg, what counts as working capital, and the true-up mechanics | Present in roughly 90 percent of deals and settled after closing, so it changes the amount actually paid |
| Earnout | Targets, measurement, control of the business, and dispute resolution | Converts fixed consideration into contingent consideration you may never receive |
| Indemnity cap and basket | The ceiling on seller liability and the threshold before claims can be made | Sets the worst case, and the gap between a capped and an uncapped item can exceed the purchase price |
| Survival period | How long the buyer can bring a claim on each category of representation | Determines how long proceeds stay at risk after they have been received |
| Escrow or holdback | Amount, duration, release mechanics, and partial release | Delays a defined share of the price and exposes it to claims |
| Non-reliance and fraud carve-outs | Whether claims can be brought on statements outside the agreement | Decides whether a management presentation becomes a liability |
Table 2: The most-negotiated terms beyond price, and why each one matters economically.
The indemnification clauses and the escrow terms are best negotiated as one package rather than separately. A seller who concedes a broad indemnity and then negotiates escrow on its own has conceded twice, because the escrow is the mechanism that funds the indemnity.
| Did You Know
Double materiality scrapes, which remove materiality qualifiers from representations for both breach and damages purposes, appeared in 82 percent of deals in the latest ABA study, up from 69 percent two years earlier. A term that was contested a few years ago is now close to standard, which is worth knowing before you spend negotiating capital resisting it. Source: ABA 2025 Private Target Deal Points Study |
Where the Market Sits Right Now
The strongest argument in any deal point conversation is where the market sits, and on several terms it has moved a long way in two years. Warranty insurance is the reason.
| Deal point | 2023 | 2025 | What it means for your negotiation |
|---|---|---|---|
| Reference to warranty insurance | 55% | 63% | Check whether the deal will be insured before negotiating caps, because the insurer absorbs the argument |
| No survival of general reps | 30% | 41% | On insured deals, arguing survival periods may be arguing about nothing |
| Indemnity coverage for alleged breaches | 17% | 27% | Buyers increasingly get coverage for claims that are alleged rather than proven |
| Earnouts used | 26% | 18% | Lowest since 2006, so an earnout proposal is less “standard” than a buyer may imply |
| Median indemnity cap, insured deals | n/a | 0.25% | Against a traditional band of 8 to 12 percent, which is the scale of the shift |
Table 3: Selected deal points from the ABA study, comparing the 2023 and 2025 editions.
The practical consequence is that a negotiation run on 2019 assumptions wastes effort. If the buyer is placing a policy, the seller’s exposure on non-fundamental representations may be limited to the retention, and the real conversation is about who pays the premium, what the policy excludes, and which items the insurer will not cover and therefore stay with the seller. Negotiating a cap from twelve percent down to eight on a deal that will be insured is a win worth almost nothing.
| Worth Knowing
Express non-reliance provisions appeared in 81 percent of deals in the latest study, and 85 percent of agreements included a fraud carve-out, with 70 percent of those limiting the carve-out to representations made inside the agreement itself. The effect is that statements made in a management presentation or a data room summary increasingly cannot be relied on, which cuts both ways depending on which side you sit. Source: Wagner Hicks analysis of the 2025 ABA study |
Why an Earnout Shifts Control to the Buyer
Earnouts get proposed as a way to bridge a valuation gap, and on paper that is what they do. The data on how they are drafted should change how a seller responds to one.
Earnouts appeared in 18 percent of deals in the latest ABA study, the lowest proportion since 2006. More telling is what the surviving earnouts contain. Only 14 percent of those deals required the buyer to operate the business consistently with past practices during the earnout period. Buyers, as the study puts it, uniformly resist covenants limiting their operational freedom.
Read that plainly. In most earnout deals the seller has agreed that part of the price depends on the performance of a business the buyer now controls, without any commitment about how that business will be run. The buyer can reallocate the sales team, change pricing, fold the product into a bundle, or shift costs onto the acquired entity, and none of that breaches an agreement that contains no operating covenant.
If you accept an earnout, negotiate four things: an operating covenant requiring the business to be run consistently with past practice, a defined and auditable measurement method, access to the records needed to verify the calculation, and a dispute mechanism that does not require litigation. If the buyer resists all four, the earnout is not consideration. It is an option the buyer holds and you have paid for.
| Common Mistake
Accepting an earnout without asking who controls the numerator. In the latest ABA study, only 5 percent of earnout deals required the buyer to operate the business so as to maximize the earnout. The absence of that covenant is the norm rather than an oversight, so it has to be negotiated in rather than assumed. Source: Wagner Hicks analysis of the 2025 ABA study |
Mistakes That Cost Real Money
Six failures recur, and none of them is about technique.
- Granting exclusivity before the terms are settled. The single most expensive mistake available, because it removes your alternatives while most of the agreement is still unwritten.
- Negotiating price in isolation. A higher number with a worse adjustment mechanism and a larger escrow can pay out less than a lower number with clean terms.
- Letting diligence run without a deadline. An open-ended review gives the buyer time to accumulate repricing arguments and leaves you no means of pressing for a close.
- Overstating anything. A number that cannot be supported in diligence costs more than the point it was meant to win, because it puts every other representation in question.
- Boxing the other side in. A counterparty with no acceptable path forward walks, and a deal that dies at the definitive agreement stage has already consumed months and fees.
- Treating the relationship as disposable. Where management is staying on or consideration includes buyer stock, you are negotiating with people you will work for.
How the Diligence Record Changes Your Position
Negotiating position in the middle phases comes down to what each side can verify. Buyers reprice what they cannot confirm, and that is the mechanism that turns disorganized records into a lower number.
Three areas produce most of the repricing arguments: normalized earnings, where add-backs are argued rather than observed; working capital, where the peg gets set from monthly data the buyer may not have seen; and contracted revenue, where renewal terms and change-of-control clauses sit inside individual contracts rather than in a summary schedule. A seller who can answer all three quickly, with documents attached, removes the uncertainty those arguments are built on.
That work happens in a due diligence data room, and two capabilities affect the negotiation directly. EZ Q&A, CapLinked’s structured question and answer module, keeps each answer attached to its question and the supporting document, so the same question asked by three workstreams gets one consistent answer rather than three slightly different ones.
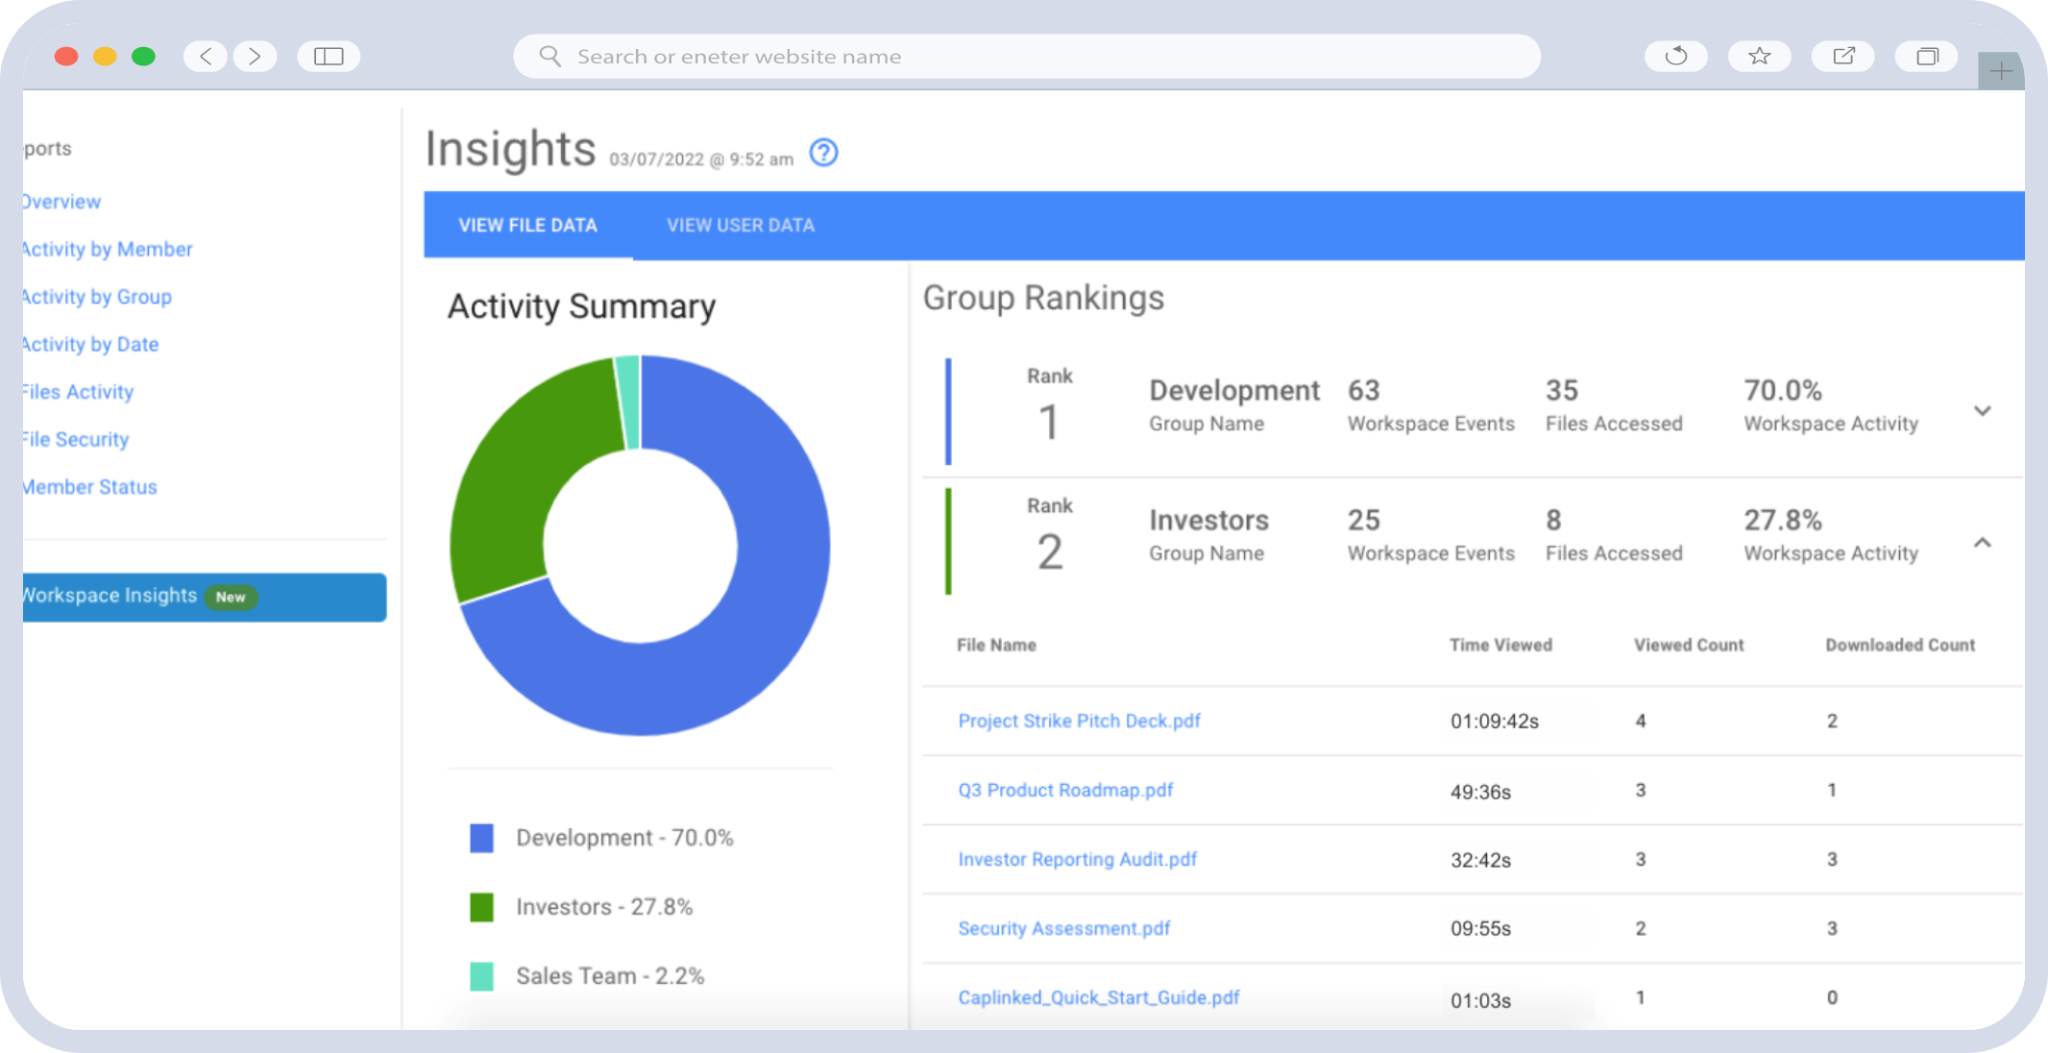
Inconsistent answers are where repricing arguments start. Activity reporting shows which documents a buyer opened and for how long, which tells you where their concerns sit ahead of the next conversation, though it shows engagement rather than intent and should not be read as a signal about their final position.
FileProtect, the digital rights management layer, revokes access to files a party already downloaded, which matters when a bidder exits and you are still running a process with others. The broader features a deal team should expect from a virtual data room are worth reviewing before a process opens rather than during one.
What to Settle Before You Grant Exclusivity
Everything above converges on one decision point. Once you sign exclusivity you have agreed not to talk to anyone else, and the definitive agreement gets drafted in that condition. Six things belong on the table first.
- Structure, named explicitly. Merger, stock purchase, or asset purchase, with the tax consequence understood by both sides.
- Whether the deal will be insured, and who pays. This determines what the rest of the risk negotiation is even about.
- The indemnity cap and survival periods in principle. Not final drafting, but a stated range, so the markup starts from an agreed position.
- The working capital peg methodology. Agree how it will be calculated, not just that there will be an adjustment.
- Earnout terms in full, if there is one. Including the operating covenant, the measurement method, and the dispute process.
- A diligence deadline and an exclusivity end date. Exclusivity without an expiry hands the buyer unlimited time at no cost to themselves.
A letter of intent that covers those six is longer and harder to agree than one that covers price and structure alone. It is also the difference between negotiating the definitive agreement from an agreed framework and negotiating it from whatever the buyer’s counsel drafts first.
| Running a process this quarter?
If the terms above depend on documents a buyer has to be able to verify quickly, the room structure decides how fast the answers arrive. Review the published pricing or start a 14-day free trial and build the room before the process opens. |
M&A Negotiation Questions Deal Teams Ask Most
What is M&A negotiation?
M&A negotiation is the process of agreeing price and allocating risk between buyer and seller, first in a letter of intent covering price, structure and exclusivity, then in a definitive agreement covering representations, indemnity, survival and closing conditions.
What gets negotiated besides price?
The working capital adjustment, any earnout, the indemnity cap and basket, survival periods, escrow amount and duration, closing conditions, and non-reliance and fraud carve-outs. Several of these move more cash than a point of price.
When does a seller have the most negotiating power?
Before exclusivity, particularly with more than one interested party. Power shifts to the buyer through diligence and is weakest during the definitive agreement markup, which is when the most consequential terms are drafted.
How has warranty insurance changed M&A negotiation?
It moved the indemnity argument to the insurer. With insurance referenced in 63 percent of private deals and no survival of general reps in 41 percent, the negotiation shifts to the retention, the exclusions, and who pays the premium.
Should a seller accept an earnout?
Only with an operating covenant, a defined measurement method, verification rights, and a dispute mechanism. Only 14 percent of earnout deals require the buyer to run the business consistently with past practice.
What is the most common M&A negotiation mistake?
Granting exclusivity before the material terms are agreed. It removes the seller’s alternatives while most of the definitive agreement is still unwritten, and every later concession is made without competitive pressure.
How do you prepare for an M&A negotiation?
Set a walk-away number net of fees, escrow and tax, build a credible alternative, anchor price on comparable transactions, find your own diligence problems first, and engage transaction counsel before the letter of intent.