Key Takeaways
- A PPM is a liability-management document first. Its job is accurate, complete disclosure, not persuasion.
- Regulation D decides when a PPM is effectively required, but antifraud liability applies to every offering, so most issuers prepare one anyway.
- The risk factors section does the most legal work and should be specific to the business, not boilerplate.
- Private equity and venture fund PPMs follow a different structure built around the fund’s terms, the GP and the limited partnership agreement.
- PPMs are distributed and tracked through a data room, which keeps a record of who received which version and when.
Table of Contents
ToggleA private placement memorandum (PPM) is the disclosure document an issuer gives prospective investors in a private securities offering. It describes the business or fund, the terms of the securities, the risks and how the money will be used, and it protects the issuer as much as it informs the investor.
This guide is written for the people who commission and distribute PPMs: general partners raising a fund, placement agents and bankers running an offering, and CFOs of companies raising private capital. It covers when a PPM is required under Regulation D, what it must include, how to prepare one step by step, how fund PPMs differ, what drives cost, and how to share a PPM securely with prospective investors.
What Is a Private Placement Memorandum (PPM)?
A private placement memorandum is the legal document a company or fund provides to prospective investors when it sells securities in a private placement. It describes the issuer, the offering terms and the risks of the investment. Private placements are exempt from SEC registration, most often under Regulation D, but they are not exempt from the antifraud provisions of federal and state securities law. That is why the PPM matters: it is the issuer’s record of what it told investors before they committed money.
Securities counsel normally drafts the PPM together with the issuer’s management, who supply the facts and stand behind them. The finished document usually travels with a subscription agreement, the governing documents of the issuer and, for larger offerings, audited financial statements.
PPM vs. Offering Memorandum
The terms are often used interchangeably. “Private placement memorandum” is the common label for Regulation D offerings by companies and funds. “Offering memorandum” or “private offering memorandum” is more common in real estate syndications and in Rule 144A debt offerings sold to institutional buyers. In M&A, the closest cousin is the confidential information memorandum, which describes a company for sale rather than a security being offered. CapLinked’s guide to the CIM for private equity buyers explains how that document differs.
When Is a PPM Required? Regulation D Basics
Regulation D does not require a PPM for an offering sold only to accredited investors. If a Rule 506(b) offering includes any non-accredited investors, however, the issuer must give them specified disclosure, including financial statements, which in practice means a PPM. And because antifraud liability applies to every offering, most issuers prepare a PPM even when the rules do not mandate one.
| Rule 504 | Rule 506(b) | Rule 506(c) | |
| Offering limit | $10 million in any 12 months | Unlimited | Unlimited |
| Who can invest | Any number and type of investor | Unlimited accredited investors plus up to 35 non-accredited investors, who must be financially sophisticated | Accredited investors only |
| General solicitation | Restricted; depends on state law | Not permitted | Permitted |
| Accredited status check | Not applicable | No verification step required | Reasonable steps to verify required |
| Required disclosure | No federal requirement; state rules may apply | Specified disclosure, including financial statements, if any non-accredited investor participates | No mandated document; antifraud rules apply |
The SEC’s investor bulletin on Regulation D adds three points every issuer should plan for:
- Form D. The issuer must file a Form D notice with the SEC within 15 days after the first sale, meaning the date the first investor is irrevocably committed to invest. The SEC charges no fee, and a filing does not mean the SEC has approved the offering.
- State requirements. Offerings may also have to comply with state securities laws. Most states expect a notice filing and fee for Rule 506 offerings, so check each state where investors live.
- Resale limits. Most private placement securities are restricted. Under Rule 144, investors generally hold them for at least one year if the issuer does not file periodic reports with the SEC.
Who Counts as an Accredited Investor?
The SEC updated the definition in 2020. Under the current criteria, an individual qualifies with:
- Income above $200,000 in each of the past two years, or $300,000 jointly with a spouse or spousal equivalent, with a reasonable expectation of the same this year
- Net worth above $1 million, alone or with a spouse or spousal equivalent, excluding the primary residence
- A Series 7, 65 or 82 license in good standing
- A role as a director, executive officer or general partner of the issuer, or as a knowledgeable employee of a private fund that is the issuer
Entities qualify with investments above $5 million, with assets above $5 million in categories such as corporations, LLCs, trusts and family offices, when all of their equity owners are accredited, or by type, such as registered investment advisers, broker-dealers and banks. The SEC reviews the definition periodically, so confirm it at the time of each offering.
What to Include in a PPM: Checklist and Sample Table of Contents
No two PPMs are identical, but most follow the same structure. Use the sample table of contents below as a private placement memorandum checklist when you review a draft:
- Cover page and legends: the issuer, the securities offered, the exemption relied on, and the required statements that the securities are unregistered and restricted.
- Summary of offering terms: the security, price, minimum investment, offering size, closing dates and investor rights, in one place.
- The company or fund: history, business model, strategy, market and competitive position.
- Management and compensation: who runs the business, their backgrounds, and how they are paid.
- Use of proceeds: how the money raised will be spent, in categories and amounts.
- Capitalization: ownership before and after the offering, including options, warrants and convertible instruments.
- Description of securities: rights, preferences, voting, transfer restrictions and any conversion terms.
- Risk factors: the risks specific to this business, offering and security, from most to least significant.
- Conflicts of interest: related-party transactions, affiliate fees and how conflicts are handled.
- Financial information: historical financial statements and, where used, projections with stated assumptions.
- Tax considerations: a summary of material federal and state tax consequences for investors.
- Investor suitability: who may invest, including accredited investor requirements.
- Subscription procedures: how to subscribe, deliver funds and complete accreditation documents.
- Exhibits: the subscription agreement, the operating agreement, bylaws or limited partnership agreement, and financial statements.
Writing Risk Factors That Hold Up
Risk factors carry more legal weight than any other section, because they are the first place a court or regulator looks when an investor claims they were not warned. Three habits make them stronger:
- Be specific. “We depend on two customers for 60% of revenue” protects the issuer; “we may lose customers” does not.
- Order by significance. Put the risks most likely to affect the investment first, not the generic market risks every PPM repeats.
- Match the facts elsewhere. If the financial statements show a going-concern note or the cap table shows heavy dilution, the risk factors must say so plainly.
Avoid presenting a known problem as a hypothetical. A risk factor that says something “could” happen when it already has is one of the most common sources of disclosure claims.
Treat this as a structure guide, not a legal template. A downloadable private placement memorandum template filled in without counsel review is a common source of disclosure gaps, because generic risk factors and terms rarely match the actual offering.
How to Write a Private Placement Memorandum, Step by Step
Private placement memorandum preparation usually runs alongside structuring the deal itself. A typical sequence:
- Structure the offering and choose the exemption. Decide the security, the amount and the investor base, then pick Rule 504, 506(b) or 506(c).
- Engage securities counsel. Counsel drafts the legal sections and confirms the exemption and state filings.
- Gather diligence materials in one place. Collect corporate records, financials, material contracts and cap tables, ideally in the same virtual data room investors will later use.
- Draft the summary of terms. Agree on the commercial terms before writing around them.
- Write risk factors specific to the business. Cover operating, market, financial, regulatory and offering-specific risks.
- Prepare the financials and use of proceeds. Make sure the numbers match the financial statements and the model.
- Reconcile the PPM with the pitch deck and data room. Every number and claim should match across all three.
- Finalize legends and subscription documents. Counsel confirms the legends, the subscription agreement and accreditation forms.
- Distribute, track and update. Send the PPM through a controlled channel, record who received it, and issue a supplement when material facts change.
PPM Drafting Principles
- Write a clear executive summary. Some investors read only the first few pages, so the summary must be accurate on its own.
- Disclose, don’t sell. State risks, conflicts and uncertainties plainly. A promotional tone works against the document’s main purpose.
- Use plain language and consistent formatting. Clear headings, tables and defined terms make the document easier to read and harder to misread.
- Keep every investor-facing document consistent. The PPM, deck, data room and any answers to investor questions should tell the same story.
- Update, don’t overwrite. Material changes go into a dated supplement, so each investor’s version can be identified later.
Private Equity Fund PPMs: What’s Different
A private equity fund PPM describes a blind or semi-blind pool rather than a single business, so the investor is underwriting the general partner as much as the strategy. Fund PPMs for private equity, venture capital and hedge funds typically cover:
- Strategy and investment process: target sectors, deal sizes, sourcing and how decisions are made.
- Key terms: fund size, commitment period, fund term, management fee, carried interest, preferred return or hurdle, and the distribution waterfall.
- Key person and removal provisions: what happens if named principals leave, and how limited partners can remove the GP.
- Conflicts and allocation policies: how deals are allocated across funds, co-investment rights, and fees charged to portfolio companies.
- Track record: prior fund performance, presented with clear methodology, gross and net figures, and context on realized and unrealized investments.
- Exhibits: the limited partnership agreement and subscription documents, which control if they conflict with the PPM.
Registered investment advisers face additional rules on how performance is presented in fund materials, so have counsel review the track record section in particular. For the wider fundraising process, see CapLinked’s guides to data rooms for private equity and the most common private equity fundraising mistakes.
Who Prepares a PPM and What It Costs
Securities counsel drafts the PPM and takes responsibility for its legal sufficiency. Placement agents and financial advisers help shape the terms and investor materials, and the issuer’s management supplies and verifies the facts. Template services and “document mill” providers can produce a PPM cheaply, but they rarely tailor risk factors or check the offering structure, which shifts the disclosure risk back to the issuer.
Private placement memorandum cost depends on:
- Offering complexity: a single class of common stock costs less than a fund with multiple share classes or a convertible structure.
- Fund vs. operating company: fund PPMs are usually longer because of the LPA, fee and waterfall disclosure.
- Jurisdictions: each additional state or country adds filings and review.
- Financial statements: audited statements, where required, add accounting cost.
- Revision cycles: the more the terms change during drafting, the higher the bill.
Ask counsel for a fixed-fee or capped estimate based on these factors before drafting begins. Arriving with organized materials, including financial statements, the cap table, governing documents and material contracts, shortens the first drafting cycle and keeps the estimate realistic.
Why Raise Capital Through a Private Placement?
Private placements remain the main route for companies and funds to raise capital without a public offering.
Less Public Exposure
Private placements avoid the public disclosure and scrutiny that come with a registered offering, which keeps sensitive plans and financials among a limited group of investors.
Faster Access to Capital
Without SEC registration and review, an issuer can move from term sheet to closing in weeks rather than the months a public offering usually takes.
Lower Cost and More Flexibility
Issuers avoid underwriting and registration costs and can structure debt or equity terms to fit the deal.
The trade-offs. Securities sold in a private placement are restricted and illiquid. Investor eligibility rules limit the pool, and Rule 506(b) bars general solicitation. Disclosure liability still applies in full, which is why the PPM matters as much in a private deal as a prospectus does in a public one.
PPM vs. Data Room: Why You Need Both
The PPM summarizes and discloses. The data room holds the underlying documents investors use to check that disclosure: financial statements, material contracts, corporate records and the exhibits themselves. It also records who received which version of the PPM and when, which matters if a disclosure question comes up after closing.
A typical capital-raise data room mirrors the PPM’s structure:
- Offering documents: the PPM, any supplements, the subscription agreement and accreditation forms
- Governing documents: the charter, bylaws, operating agreement or limited partnership agreement
- Financials: historical statements, the model behind any projections and the cap table
- Material contracts: customer, supplier, lease, debt and intellectual property agreements
- Legal and compliance: licenses, litigation, regulatory correspondence and insurance
- Investor-specific folders: side letters, questions and signed documents for each investor
The most secure way to share offering memorandums with prospective investors follows a few practices:
- NDA before access. Require investors to accept confidentiality terms before they see any documents.
- Individually identifiable copies. Dynamic watermarks are the modern version of numbered PPM copies.
- View-only access for drafts. Limit downloads until the document is final.
- Version control for supplements. Keep every version and make it clear which one is current.
- One secure place for subscriptions. Collect signed subscription agreements and accreditation documents in the same room, not over email.
How CapLinked Helps Fund Managers and Issuers Distribute PPMs
CapLinked’s financing workspaces are built to distribute a PPM, support investor diligence and keep a record of both.
For GPs Raising a Fund
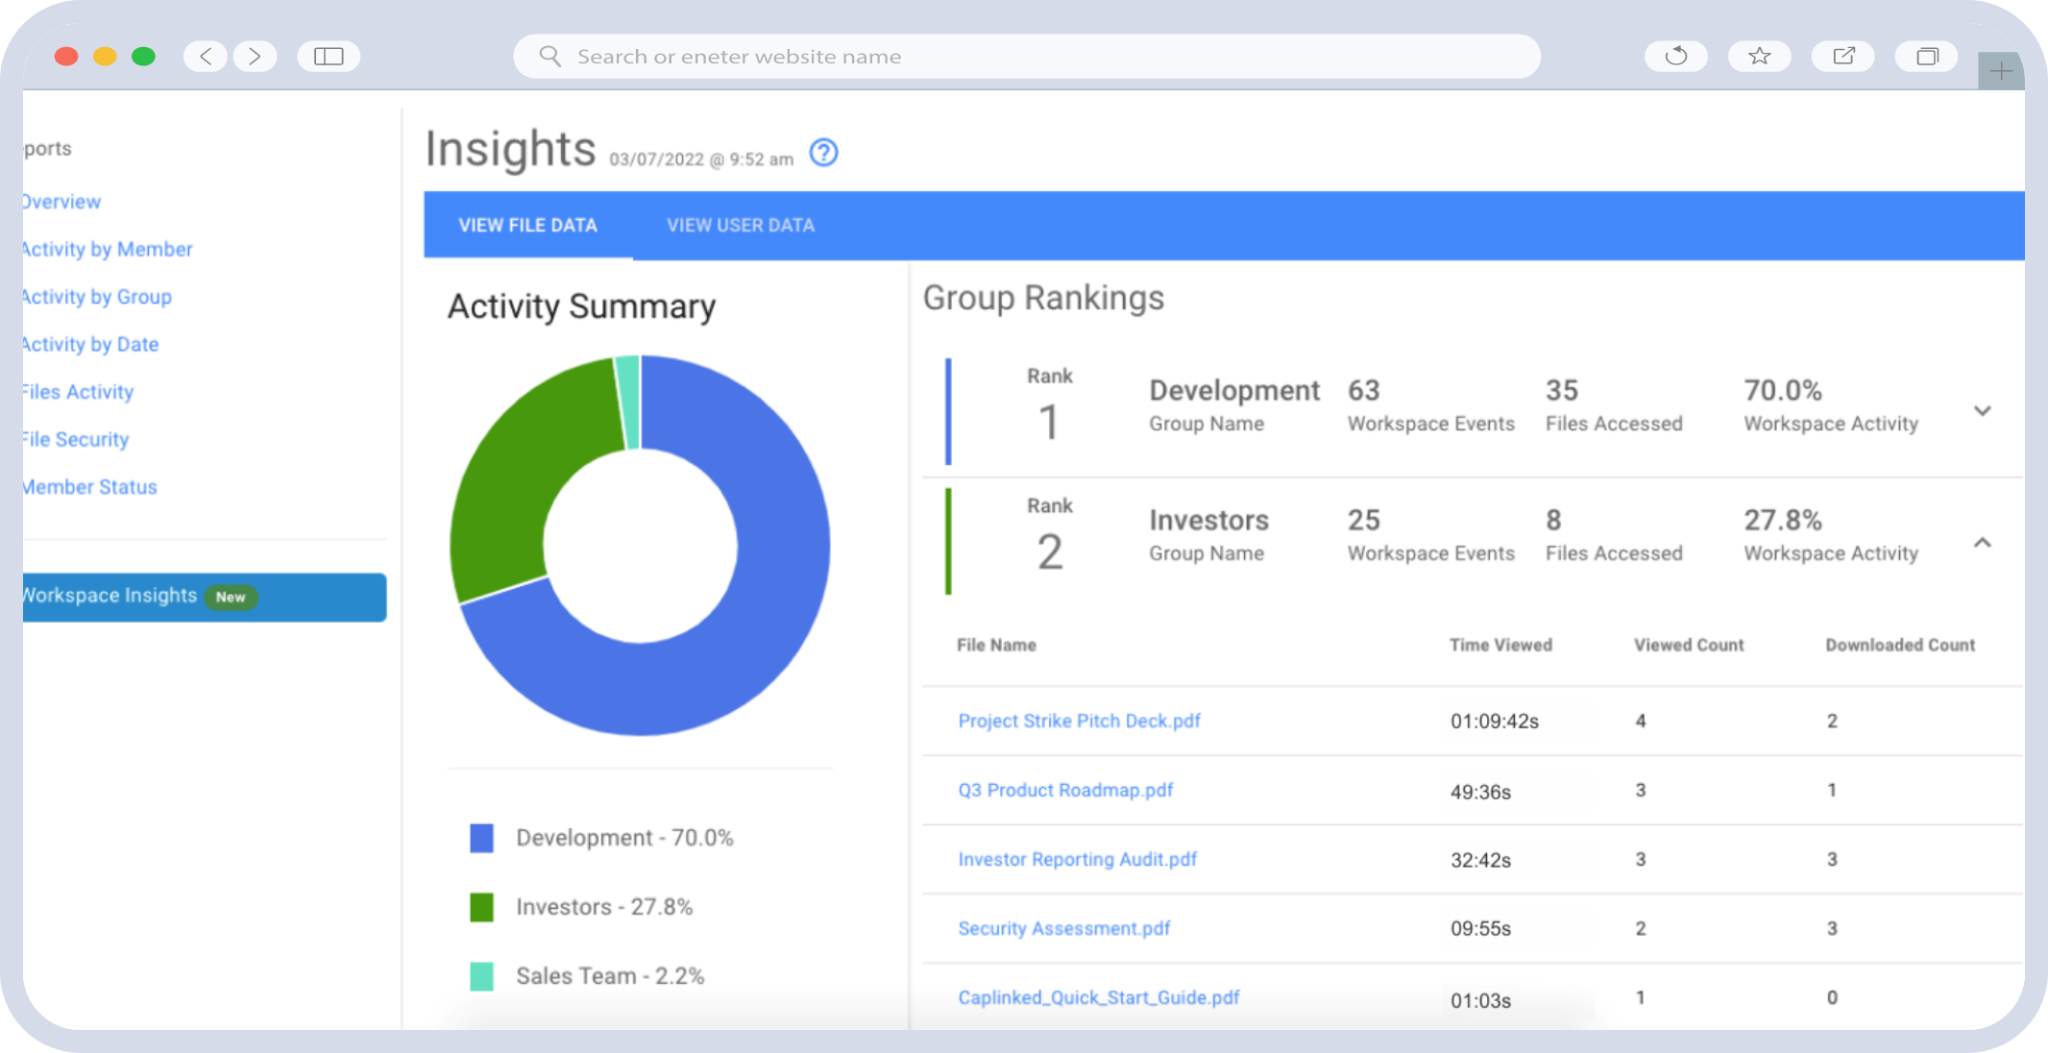
Set up a shared folder with the PPM, LPA, risk disclosures and subscription documents for all prospective limited partners, plus a private folder for each investor’s side letter and questions. EZ Insights and Activity Tracker reporting show which groups and investors are most engaged and how often each file is viewed and downloaded. After the final close, the same workspace can serve investor reporting for quarterly statements and tax documents.
For Placement Agents and Bankers
Require a custom NDA or terms of access before entry, and give each investor or syndicate its own permission group with access to only the folders it should see. Dynamic watermarks show each viewer’s email, IP address, date and time, and FileProtect digital rights management lets you revoke access to a file even after it has been downloaded. EZ Q&A routes questions to the right expert and keeps an FAQ, so every investor gets the same answer.
For Companies Raising Capital
Issue PPM supplements with file versioning and new document notifications, so investors see the current version and get an alert when it changes. Collect signed subscription agreements and accreditation documents in a dedicated folder, use bulk invites or the Salesforce integration to bring investors in, and apply custom branding so the room carries the issuer’s name.
Every workspace has SOC 2/SSAE 18 Type II security, runs on ISO 27001-certified AWS infrastructure and uses 256-bit AES encryption at rest. Start a 14-day free trial to set up your offering room.
PPM FAQs
Is a PPM required for a Reg D offering?
Not always. Regulation D does not require a PPM for offerings sold only to accredited investors. A Rule 506(b) offering that includes non-accredited investors must provide them with specified disclosure, including financial statements. Because antifraud liability applies to every offering, most issuers prepare a PPM regardless of the exemption they use.
What is the difference between a PPM and an offering memorandum?
The terms are often used interchangeably. “Private placement memorandum” is the usual label for Regulation D offerings by companies and funds, while “offering memorandum” is common in real estate syndications and Rule 144A debt deals. Both are disclosure documents describing the issuer, the securities, the terms and the risks.
What should a PPM include?
A PPM typically includes a cover page with legends, a summary of offering terms, a description of the company or fund, management and compensation, use of proceeds, capitalization, a description of securities, risk factors, conflicts of interest, financial information, tax considerations, investor suitability, subscription procedures and exhibits such as the subscription agreement.
How much does a private placement memorandum cost?
Cost depends on offering complexity, whether the issuer is a fund or an operating company, the number of jurisdictions, the financial statements required and how many revision cycles the terms go through. Fund PPMs usually cost more than simple equity offerings. Ask securities counsel for a fixed-fee or capped estimate.
What is a PPM in private equity?
In private equity, a PPM is the offering document a general partner gives prospective limited partners when raising a fund. It describes the strategy, the team, the track record and key terms such as fees, carried interest, the distribution waterfall and key person provisions, with the limited partnership agreement attached.
How should a PPM be shared with investors?
Share a PPM through a secure data room rather than email. Require an NDA before access, apply dynamic watermarks to each copy, limit downloads on drafts, keep version control for supplements and track who opened which version. Collect signed subscription and accreditation documents in the same secure workspace.