Key Takeaways:
- An M&A strategy is the standing plan that says why a company will acquire, what kind of target fits, and how deals will be integrated once they close.
- It is narrower than corporate strategy. Corporate strategy decides where the company competes; the M&A strategy decides which of those goals are best reached by buying rather than building.
- The building blocks are strategic alignment, target screening, due diligence, valuation and negotiation, integration planning, and change management.
- Integration approach is a second lens. Standalone, absorption, combination, and transformational deals differ in how much of the two businesses actually merge.
- Most acquisitions are chasing one of seven things, from performance improvement to a bargain price, and the honest ones name which.
- Global deal value rebounded sharply in 2025, driven by megadeals rather than by more transactions.
- An M&A program improves only when it is measured, and the most useful single measure is the effective multiple paid once synergies have actually landed.
Table of Contents
ToggleAn M&A strategy is a company’s standing plan for using acquisitions to reach its business goals. It defines why the company will buy rather than build, what a good target looks like, how much it is worth paying, and what happens to the acquired business after the deal closes.
Mergers and acquisitions are extremely common types of transactions in the business world, and knowing the ins and outs of them is one of the keys to success. Global deal value reached roughly $4.8 trillion in 2025, up around 36% on the previous year and the second-highest annual total on record, according to Bain & Company. Notably, the deal count barely moved. The rebound came from megadeals rather than from more companies buying, which tells you something about who is transacting and why. Odds are that your company (or a company you’re involved with) will go through the process eventually, so knowing what an M&A strategy is, and what separates a good one from a wish list, is worth the time.
What Is an M&A Strategy?
To put it simply, M&A strategies are the driving force behind a business deal. In virtually every instance, M&As are undertaken either for financial purposes or to reduce the risk for the acquiring company.
It helps to separate this from corporate strategy, because the two get used interchangeably and they are not the same thing. Corporate strategy decides where a company competes: which markets, which products, which customers, and what it wants to be known for. The M&A strategy sits underneath that and answers a narrower question, namely which of those goals are better reached by buying a company than by building the capability internally or partnering for it. A company without a clear corporate strategy cannot have a coherent M&A strategy, only a list of things it might buy.
This is also what separates a strategy from opportunism. A real M&A strategy exists before the banker’s call comes in, and it is what lets a company say no quickly to a target that does not fit.
Financial buyers and strategic buyers
In most instances, buyers fall under one of two categories.
- Financial buyers: These are the ones who buy for the goal of financial gain. There may be several end games here, such as increasing cash flow, growing market share, or reducing debt, but the transaction is always financially motivated.
- Strategic buyers: A strategic buyer has goals beyond those of a financial buyer, though some of them will overlap. These include acquiring companies to gain new products or expertise, expand offerings, or gain inroads into new territories.
In many instances, these investors are private equity (PE) or venture capital (VC) firms. Although they are similar in many ways, VC firms tend to nurture newer and smaller companies than PE firms do, while PE firms go with a longer-term strategy, buying and holding the target companies before cashing out.
How Mergers and Acquisitions Work
Mergers and acquisitions (M&As) are a type of business transaction in which two companies, a buyer (the acquiring company) and a seller (the target company), combine assets. Naturally, there are multiple types of M&As, such as horizontal mergers and acquisitions (one company buys out a competitor), vertical mergers and acquisitions (two companies in a similar industry but occupying different spots in the supply chain), and conglomerate mergers and acquisitions (where two companies in different industries combine), among others.
Legal structure is a separate choice from strategic type. The same commercial deal can be executed as a direct merger, an asset purchase, or a triangular structure, and the difference between a forward merger and a reverse triangular merger affects tax treatment, contract assignment, and which liabilities travel with the deal. Strategy sets the target; structure sets the mechanics.
What Are the Key Components of an M&A Strategy?
These are the building blocks a company needs standing before any specific deal appears. The section after next covers the sequence a single transaction moves through; this one covers the capabilities that make that sequence work.
- Strategic alignment. A written statement of which corporate goals acquisitions are meant to serve, and which they are not. Without it, every target looks plausible and the deal team ends up arguing about fit after the price has been discussed.
- Target screening. A defined set of criteria, such as size, geography, business model, margin profile, and cultural markers, applied to a maintained pipeline rather than assembled reactively when a bank sends a teaser.
- Due diligence. The verification layer across commercial, financial, legal, tax, and technical workstreams. A repeatable request list and a due diligence data room structure that gets reused deal to deal is what turns diligence from a scramble into a process.
- Valuation and negotiation. A view on what the target is worth with and without synergies, a walk-away number set before negotiation starts, and a deal structure that allocates risk through earn-outs, escrows, or indemnities where the diligence found gaps.
- Integration planning. Planning that begins during diligence, not after close. Who owns which system, which customers get told what and when, and which synergies are being counted in the price.
- Change management. The people side. Retention of the staff who make the target valuable, a clear operating model on day one, and honest internal communication. This is where most of the value quietly leaks.
M&A Strategy by Integration Approach
The seven motivations further down explain why a company buys. Integration approach is the complementary lens, and it explains how much of the two businesses actually merge afterward. The right answer depends on how similar the two business models are and how large the target is relative to the buyer.
| Approach | What happens | Fits when |
|---|---|---|
| Standalone | The target keeps its systems, brand, and operating model. Only reporting and governance connect. | Business models differ, or the value is in the target staying exactly as it is |
| Absorption | The target is folded into the buyer’s systems, processes, and brand, and largely disappears as a separate entity. | Business models are similar and the target is small relative to the buyer |
| Combination | Both sides adopt the best of each, and functions are merged selectively rather than wholesale. | The two are comparable in size and each has capabilities worth keeping |
| Transformational | Both businesses are reshaped into something neither was before. | The deal is a bet on a new operating model, not on synergies from the existing ones |
Two rules of thumb. The greater the difference in business models, the more standalone the approach should be, because forcing a dissimilar business onto shared systems destroys the thing that was bought. And the closer the two are in size, the harder absorption becomes, because a large target will not simply accept the buyer’s way of working.
How the M&A Strategy Process Works, Step by Step
This is the sequence a single transaction runs through, from intent to integration.
- 1. Define the acquisition thesis. State what the company is trying to achieve and why acquiring is the right route, as opposed to building or partnering.
- 2. Build and screen the pipeline. Apply the screening criteria to a maintained list of candidates and rank them, rather than reacting to whatever comes over the transom.
- 3. Make contact and sign an LOI. Approach the target, agree on high-level terms, and secure an exclusivity window in which to do the work.
- 4. Run due diligence. Commercial, financial, legal, tax, and technical workstreams run in parallel against the clock the LOI set. Findings feed the price and the structure. This stage lives or dies on how fast documents move between the parties, which is why secure document sharing with tracked access matters more here than anywhere else in the process.
- 5. Value the target and negotiate. Set the price against the diligence findings, decide which synergies you are willing to pay for upfront, and allocate the remaining risk through deal structure.
- 6. Sign, clear, and close. Definitive agreements, regulatory clearance where required, and financing all have to land before the deal completes.
- 7. Integrate and track. Execute the integration plan built during diligence, then measure what actually happened against what was promised.
Why Companies Acquire, and What They Are Chasing
These are the motivations behind a deal rather than the strategy itself. A strategy names which of these it is pursuing and why acquiring beats the alternatives; a wish list just gestures at several of them at once.
As mentioned earlier, there are multiple reasons why one company would acquire another. While every situation is different, the goal is to increase value or reduce risk. In nearly every instance below, there is overlap with the different strategies. Most mergers and acquisitions fall under one of the following categories.
1. Improve performance
This is to increase value or reduce expenses, both of which promote growth and boost earnings per share (EPS), thus increasing overall value.
2. Acquire technology, products, and resources
In this instance, a company is acquired because it is less expensive or time-consuming to develop this technology, product, or resource on its own. This includes intellectual property (IP), trade secrets, technology, or customer base.
3. Take advantage of economies of scale
A company can dramatically lower costs by acquiring another one with similar products. For example, rather than expanding production capabilities from scratch, buying an existing operation with that infrastructure in place can produce profits faster and require less investment.
4. Invest in promising startups
Although this is more of a VC strategy (investing in a startup with future potential), this overlaps with acquiring technology, products, and resources. Gaining the products, services, or technologies from a startup can be a fast track to future financial gains.
5. Expansion
This is a way to gain traction with your core competencies in new markets, which is often a far speedier process than organic growth. In addition, acquiring a company with related products but a similar customer base can accelerate expansion and growth.
6. Consolidation
Acquiring a competitor also plays into expansion, but it has ties with financial performance as well. Consolidation can be used to reduce price competition by eliminating competitors, or to reduce capacity by scaling down an industry’s excess supply or production capacity.
7. Grab a bargain
Everybody loves a great deal, and when one presents itself, it may be too good an opportunity to pass up. In this instance, it is more of a financially driven deal than a strategic one.
In addition, there are other motivations under the M&A umbrella, all of which fit under one or more of the categories above. These include taking steps to reduce tax liability, deploy excess cash, achieve vertical integration, and even transform a business.
What Do Real M&A Strategies Examples Look Like?
Four deals, and the strategic logic behind each.
Union Pacific and Norfolk Southern, consolidation
The 2025 rail merger is consolidation in its clearest form: two operators in the same industry combining to create a single transcontinental network. It was one of the largest deals of a record year, and the logic is route density and cost per ton-mile rather than any new capability. Deals like this live or die on regulatory clearance, which is why consolidation strategies need a realistic view of antitrust risk before the first approach.
Microsoft and Activision Blizzard, acquiring products and IP
Microsoft paid a reported $69 billion for a games catalog it could not have built, on a timeline that mattered. This is the second motivation on the list, executed at scale: the value sat almost entirely in intellectual property and the studios that produce it, which also made retention the central integration risk. Nearly two years of regulatory review across three jurisdictions is the other lesson here.
Amazon and Whole Foods, expansion into a new channel
Amazon bought physical grocery presence rather than building it store by store, gaining several hundred locations and a customer base in a category where online penetration had stalled. The strategic read is expansion, and the integration approach was closer to combination than absorption, since the brand and store experience were worth preserving rather than folding into Amazon.
The Warner Bros. Discovery contest, scope over scale
The bidding for Warner Bros. Discovery, one of the defining stories of 2025 dealmaking, is a scope deal: buyers chasing content libraries and subscriber reach rather than cost synergies in an existing business. Bain found that 60% of deals above $1 billion in 2025 were scope rather than scale, the highest share ever recorded, which makes this less an outlier than a marker of where dealmaking has moved.
What Are the Best Practices for M&A Strategy?
- Write the thesis down before you look at targets. A thesis written after a target appears will be reverse-engineered to justify it. Written first, it becomes a filter.
- Acquire regularly rather than occasionally. Programmatic acquirers, making steady small-to-mid-size deals against a consistent thesis, tend to outperform companies that make one large bet every few years. Repetition builds the muscle.
- Set the walk-away price before negotiation, and honor it. Deal momentum is the most expensive force in M&A. A number agreed in advance, with the synergies you are willing to pay for made explicit, is the only reliable defense.
- Start integration planning during diligence. The people who find the risks should be the people who plan around them. Handing a deal to an integration team at close loses most of what diligence learned.
- Name an integration owner with real authority. Not a committee, and not the deal lead who is already onto the next transaction.
- Treat retention as a priced item. If the value is in people or IP the people maintain, retention packages are part of the purchase price, not an afterthought.
- Standardize the deal infrastructure. Reusable diligence checklists, folder structures, permission templates, and reporting. Serial acquirers running several processes at once need enterprise-level information control so that one deal’s materials never surface in another’s room.
- Be willing to walk away. A strategy that has never produced a no is not a strategy.
How Do You Measure Whether an M&A Strategy Worked?
Most companies stop measuring at close, which is precisely when the useful information starts. Share price movement on announcement day tells you what the market guessed, not what happened.
A single north-star metric works better than a dashboard: the effective multiple paid, calculated twelve months after close. Take the price paid and divide it by the target’s run-rate earnings at the twelve-month mark, including the synergies that have actually landed rather than the ones that were modeled. If a business was bought at 12 times earnings and realized synergies bring the effective multiple down to 8, the thesis held. If it has drifted up to 14 because revenue slipped or synergies never materialized, the price was wrong regardless of how the deal looked on announcement.
Two feedback loops sit around that number:
- Structured post-mortems. A written review of every deal at twelve and twenty-four months, comparing what was assumed against what occurred, circulated to the people who will run the next one. Not a blame exercise, and not optional.
- Employee surveys at the target. Run at thirty, ninety, and three hundred and sixty-five days. Attrition data tells you people have already left; survey data tells you they are about to, while there is still time to act.
The underlying point is that M&A capability is learned rather than innate. Companies that measure and review get better at it; companies that close deals and move on repeat the same mistakes at increasing scale.
The Role of a Virtual Data Room in Any M&A
A virtual data room (VDR) has always been an indispensable tool for M&As in multiple industries. A VDR is a secure online location where all parties to the transaction can store, share, and edit all documentation related to the process. The features of a quality VDR include secure access with enterprise-level encryption, multiple layers of security, and user-friendly admin controls. There are also customizable rights management features that grant only approved users access to certain documents, which increases the security of the deal and maintains the integrity of the data.
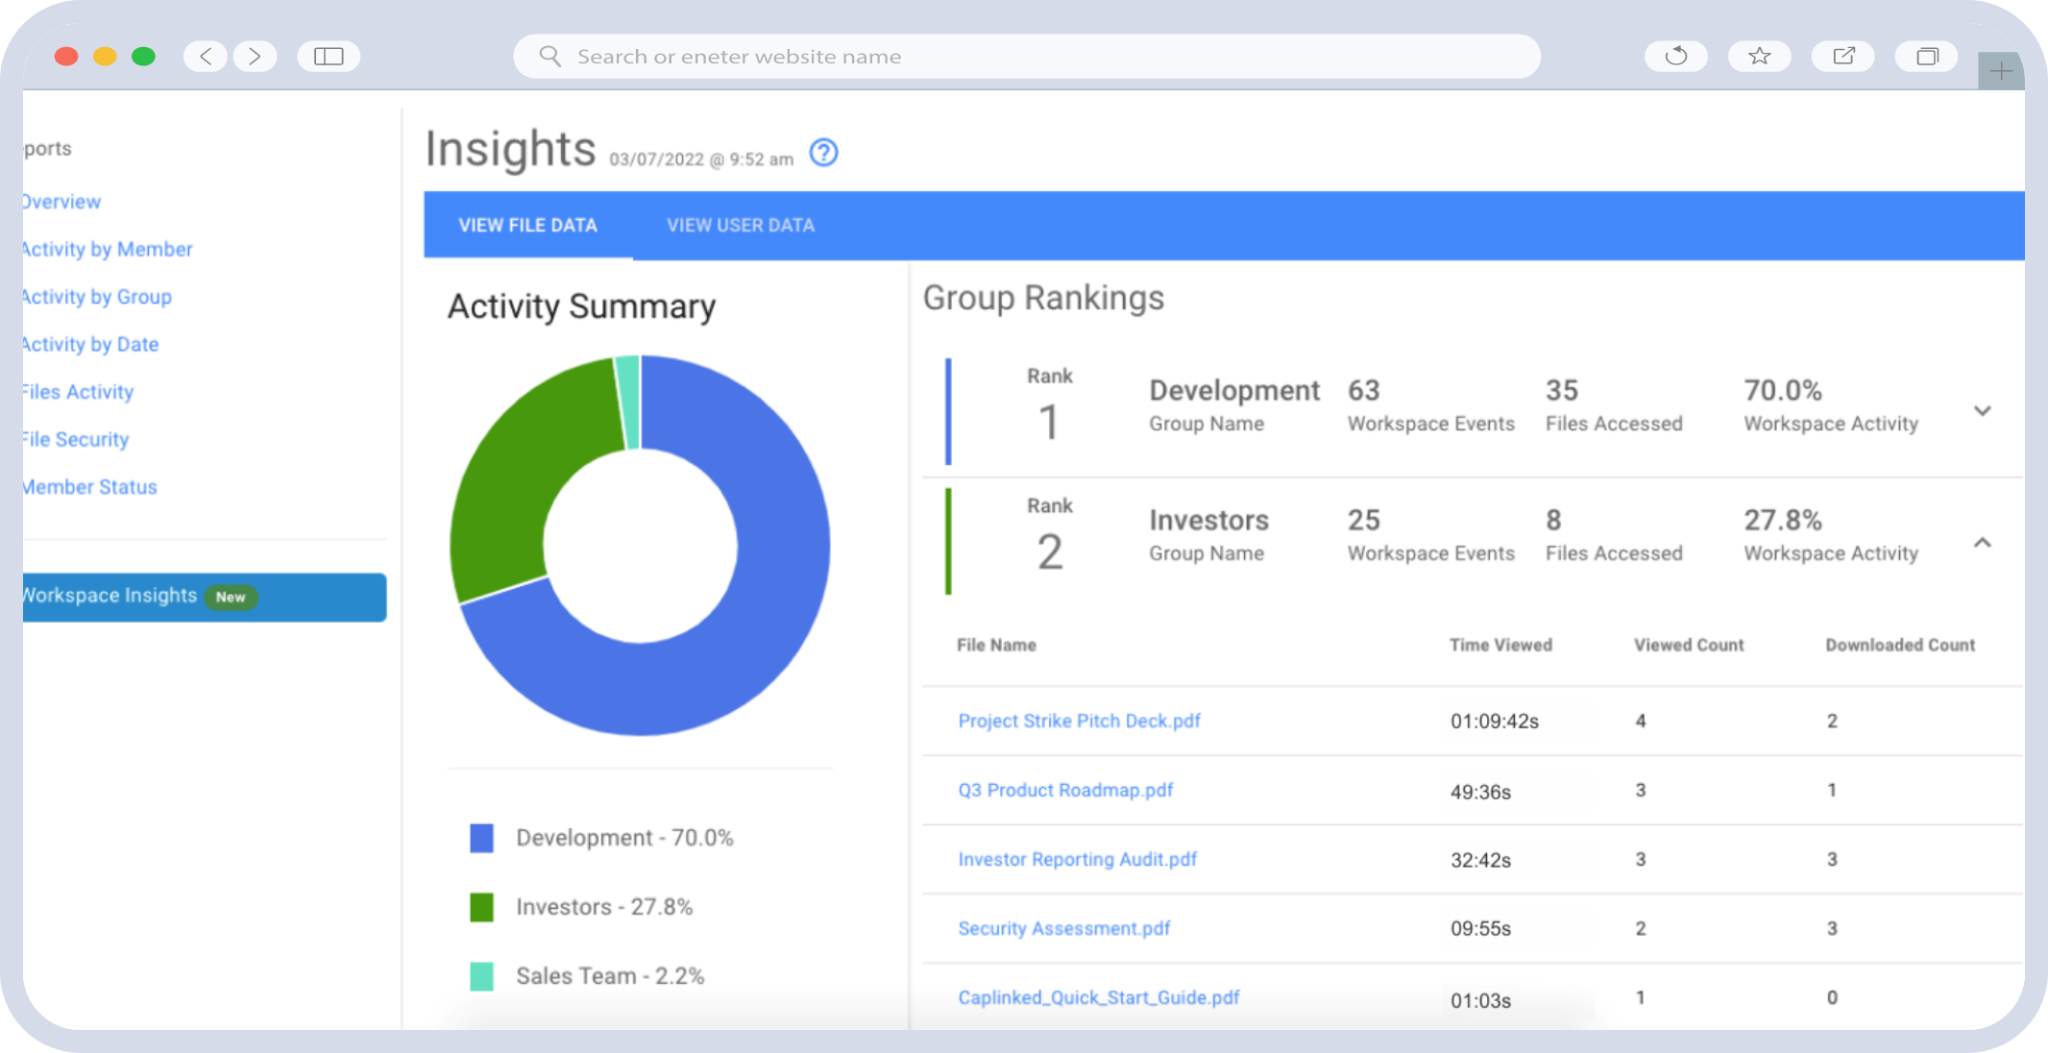
Where a data room earns its keep is in the gap between strategy and execution. An acquisition thesis is only as good as the diligence that tests it, and diligence moves at the speed documents move. CapLinked is built for that stretch of the deal. Rooms launch in minutes without plugins, bulk upload indexes documents automatically as they land, and permission templates mean the structure does not need rebuilding for the next target in the pipeline. EZ Q&A threads every buyer question against the document it refers to, so a seller answers once rather than four times across four inboxes. FileProtect digital rights management restricts printing, forwarding, and downloading, and allows a remote shred when a bidder drops out of the process.
Full audit trails record every view, which is the record you want when a valuation is challenged later. An open API and integrations connect the room to the systems the deal team already uses, and Concierge handles setup and administration when a lean corporate development team is running several processes at once.
CapLinked is an industry leader in the VDR space, offering online workspaces that are highly secure yet straightforward to use. CapLinked VDRs feature an interface compatible with every type of OS, giving users the ability to upload and download documents from any computer, tablet, or smartphone anywhere in the world. Transparent pricing is published upfront, with no long-term contract required.
| See how a CapLinked VDR shortens the deal timeline and lowers costs, since no party ever has to travel to an old-school “deal room.” |
Frequently Asked Questions
What is an M&A strategy in simple terms?
It is a company’s standing plan for using acquisitions to reach its goals. It sets out why the company would buy rather than build, what a good target looks like, what it is worth paying, and what happens to the acquired business after close.
How is an M&A strategy different from corporate strategy?
Corporate strategy decides where a company competes. The M&A strategy sits underneath it and decides which of those goals are better reached by buying a company than by building or partnering. One cannot be coherent without the other.
What is an M&A strategy framework?
A repeatable structure covering strategic alignment, target screening, due diligence, valuation and negotiation, integration planning, and change management. The point of a framework is that the same steps apply to every deal, so the company gets better at them.
What is an M&A integration strategy?
The plan for how much of the acquired business merges into the buyer. The four common approaches are standalone, absorption, combination, and transformational, and the right choice depends on how similar the business models are and how large the target is relative to the buyer.
What is an M&A brand strategy?
The decision about what happens to the two brands after close: retain both, retire the target’s brand, migrate customers gradually, or create something new. It follows from the integration approach, since a standalone deal usually keeps the brand while an absorption usually retires it.
How do you measure M&A success?
The most useful single measure is the effective multiple paid twelve months after close, calculated with synergies that have actually landed rather than modeled ones. Structured post-mortems and employee surveys at the target supply the context behind that number.