Key Takeaways
- A reverse triangular merger uses three parties: the buyer, a shell merger sub, and the target, which survives as the buyer’s wholly owned subsidiary.
- Buyers choose it when the target holds contracts, licenses or permits that would be hard to transfer, because the entity holding them never goes away.
- The buyer’s own shareholders usually don’t vote, since the buyer approves as the merger sub’s sole stockholder, though stock exchange rules can require a vote on large share issuances.
- Tax treatment follows the consideration: an all-cash deal is taxed like a stock purchase, while a deal paid at least 80% in buyer voting stock can be tax-free under IRC §368(a)(2)(E).
- Every known and unknown liability stays inside the surviving target, so due diligence is the buyer’s main protection.
- A reverse triangular merger is unrelated to a reverse merger, which is how a private company goes public through a listed shell.
A reverse triangular merger is an acquisition structure in which the buyer forms a subsidiary, that subsidiary merges into the target, and the target survives as the buyer’s wholly owned subsidiary. Because the target never stops existing, its contracts, licenses and permits generally stay in place, and so do its liabilities.
Tax advisors and IRS rulings often call the same transaction a reverse subsidiary merger.
It is the structure buyers reach for when the target owns something that can’t easily be moved: a pharmaceutical license, a government contract, a payer network, a long commercial lease. None of it has to move, because the entity holding it never goes away.
The mechanics are counterintuitive the first time you see them, which is why the term causes so much confusion, including confusion with the unrelated “reverse merger” used to take a company public through a shell.
Below you’ll find the deal diagram, the steps from LOI to closing, the taxable and tax-free versions, and what the buyer inherits, each checked against SEC filings and Delaware case law.
How Do Triangular Mergers Work, and What Makes One Reverse?
A triangular merger is any merger with three parties: the buyer (the parent), a merger sub the buyer creates for the deal, and the target. The buyer sits above the merger rather than in it, supplies the consideration, and ends up owning whichever entity survives.
The direction of the merger decides which entity that is:
- Forward triangular merger. The target merges into the merger sub. The target disappears, and the merger sub survives holding the target’s assets and liabilities.
- Reverse triangular merger. The merger sub merges into the target. The merger sub disappears, and the target survives, now wholly owned by the buyer.
“Triangular” refers to the three parties, and “reverse” refers to the shell merging into the operating company. “Reverse triangle merger” and the IRS term “reverse subsidiary merger” describe the same transaction.
Basic requirements for a reverse triangular merger
The requirements below assume a Delaware target; other states follow a similar pattern, so check the target’s own statute and charter.
- Target board approval. The target’s board adopts the merger agreement and declares it advisable under Section 251 of the Delaware General Corporation Law.
- Target stockholder approval. Holders of a majority of the outstanding shares entitled to vote adopt the agreement, unless the charter sets a higher bar. Under Section 251(h), a buyer that first acquires enough shares in a tender offer can complete the merger without that vote.
- Buyer approval as sole stockholder. The buyer adopts the agreement as the merger sub’s only stockholder.
- Certificate of merger. The merger takes effect when the certificate is filed with the Delaware Secretary of State, or at a later time it specifies.
- Regulatory clearances. HSR, sector regulators and CFIUS, where they apply, must clear before closing.
Reverse Triangular Merger Diagram: Deal Structure Explained
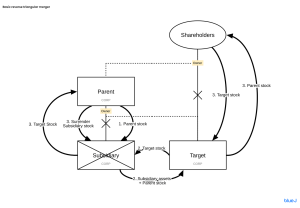
A reverse triangular merger involves the creation of a subsidiary by the acquirer, which then merges with the selling entity and ceases to exist, resulting in the selling entity becoming a subsidiary of the acquirer. This type of merger is preferred over the forward triangular merger as it retains the seller entity and its contracts.
A reverse triangular merger diagram shows three entities and one direction of travel. The three entities are where “triangular” comes from:
- The buyer (parent). The company doing the acquiring.
- The merger sub. A shell corporation the buyer forms specifically for this deal. No employees, no operations, no assets beyond what’s needed to close.
- The target. The company being acquired.
Three things happen simultaneously at the effective time: the target’s outstanding shares are cancelled and converted into the right to receive the merger consideration (cash, buyer stock, or a mix); the merger sub’s equity converts into shares of the surviving corporation; and the buyer ends up holding 100% of the target.
That’s the “reverse” part. In a forward triangular merger the target merges into the subsidiary and the target disappears. Here the direction flips, and the target is the one left standing.
Why does the direction of the merger matter?
Because the target is never dissolved, it keeps holding everything it held before. Its contracts don’t get transferred to anyone, they stay where they were, on the balance sheet of an entity that simply has a new owner.
Delaware courts have confirmed this. In Meso Scale Diagnostics, LLC v. Roche Diagnostics GmbH (Del. Ch. 2013), the Court of Chancery held that a reverse triangular merger does not constitute an assignment “by operation of law”, so it doesn’t trigger a standard anti-assignment clause in the surviving company’s contracts. The reasoning turned on Section 259 of the Delaware General Corporation Law: the assets began as the surviving entity’s property and remained its property after the merger.
The practical takeaway: a counterparty who wants consent rights over a change in ownership needs an explicit change-of-control provision, not an anti-assignment clause. Buyers should still scrub material contracts for those during diligence.
Why doesn’t the buyer need a shareholder vote?
The buyer is not a constituent party to the merger, only the merger sub and the target are. So the buyer typically doesn’t convene a shareholder vote. Its board approves, and the buyer then signs off as the merger sub’s sole shareholder. For a public acquirer, that removes a proxy process and weeks of calendar from the timeline.
Why does the direction of the merger matter?
Because the target is never dissolved, it keeps holding everything it held before. Its contracts don’t get transferred to anyone; they stay where they were, on the balance sheet of an entity that simply has a new owner.
The Delaware Court of Chancery addressed this directly. In Meso Scale Diagnostics, LLC v. Roche Diagnostics GmbH (Del. Ch. 2013), the court held that a reverse triangular merger is not an assignment “by operation of law,” so it does not trigger a standard anti-assignment clause in the surviving company’s contracts. The reasoning turned on Section 259 of the Delaware General Corporation Law: the assets began as the surviving entity’s property and remained its property after the merger, as the Harvard Law School Forum on Corporate Governance summarized at the time.
The rule is not universal. Courts applying California and New Jersey law have treated a reverse triangular merger as an assignment of certain IP licenses, so the governing-law clause in each material contract matters as much as the structure.
The practical takeaway: a counterparty that wants consent rights over a change in ownership needs an explicit change-of-control provision, not an anti-assignment clause. Buyers should still review material contracts for those provisions during diligence.
Why doesn’t the buyer need a shareholder vote?
The buyer is not a constituent party to the merger; only the merger sub and the target are. So the buyer typically doesn’t convene a shareholder vote. Its board approves, and the buyer then signs off as the merger sub’s sole shareholder. For a public acquirer, that removes a proxy process and weeks of calendar from the timeline.
One exception catches stock deals. If a listed buyer issues 20% or more of its outstanding shares as merger consideration, NYSE and Nasdaq rules generally require a buyer shareholder vote on the share issuance, even though the merger itself needs none.
What Are the Steps in a Reverse Triangular Merger, From LOI to Closing?
A reverse triangular merger moves through seven steps, and the structure shapes each one: who signs, who votes, what diligence has to find, and when the target’s contracts are tested.
- Sign the LOI and set the structure. The letter of intent names the reverse triangular merger as the intended structure and sets price, form of consideration and exclusivity. The consideration mix matters this early because it decides whether the deal can be tax-free.
- Open the data room and run due diligence. Because the target survives with its liabilities attached, focus first on change-of-control clauses in material agreements, contingent liabilities, IP assignments and tax attributes. A due diligence data room keeps requests and documents in one place, and a structured Q&A workflow keeps questions out of email.
- Form the merger sub. The buyer incorporates a shell subsidiary, usually in the same state as the target, solely to complete the merger. Amazon formed its merger sub for One Medical two days before signing.
- Negotiate the Agreement and Plan of Merger. The agreement sets the consideration, representations and warranties, interim covenants, closing conditions, indemnification and termination rights. M&A counsel drafts alongside tax advisors, since the tax structure has to be settled before signing, not after.
- Obtain board and target shareholder approvals. The target’s board adopts and recommends the agreement, and target stockholders vote unless a tender offer under DGCL Section 251(h) replaces the vote. The buyer approves as the merger sub’s sole stockholder. Dissenting stockholders who follow DGCL Section 262 can seek appraisal instead of taking the deal price.
- Clear regulatory review. Deals above the HSR thresholds need antitrust clearance, sector regulators in healthcare, financial services, energy and defense may have their own approvals, and CFIUS reviews certain foreign acquirers. This step usually sets the closing date.
| Worth Knowing
The HSR size-of-transaction threshold rose to $133.9 million for deals closing on or after February 17, 2026, up from $126.4 million. Deals valued above $535.5 million must file regardless of the parties’ size. |
- File the certificate of merger and close. Filing the certificate makes the merger effective: the merger sub’s existence ends, target shares convert into the merger consideration, and the target continues as the buyer’s wholly owned subsidiary.
Integration starts after closing, when the target’s permits, insurance and compliance programs are reviewed under new ownership; CapLinked’s guide to post-acquisition integration covers that phase.
| Opening the data room is step two of every reverse triangular merger. Set up a workspace with per-bidder permissions and a structured Q&A log before the LOI is signed. |
How Is a Reverse Triangular Merger Taxed?
The consideration, rather than the structure, decides the tax treatment of a reverse triangular merger. The same three-party merger can be fully taxable or largely tax-free depending on what the target’s shareholders receive.
How is a taxable reverse triangular merger taxed?
When target shareholders are cashed out, the transaction is treated as a stock purchase for federal income tax purposes. Target shareholders recognize capital gain or loss. The buyer takes a cost basis in the stock of the target, but the target’s assets keep their historic carryover basis. There is no step-up, and so no incremental depreciation or amortization deductions, unless the parties can make a valid Section 338(h)(10) or 336(e) election, which requires a qualifying target such as an S corporation or a member of a consolidated group.
The target’s tax attributes, including net operating losses, stay with the target, so the buyer can benefit from them, but the ownership change generally triggers a Section 382 annual limitation on how quickly those losses can be used. The saving is real but capped, and the cap often decides whether the attributes are worth pricing into the deal at all.
What are the requirements for a tax-free reverse triangular merger under §368(a)(2)(E)?
A reverse triangular merger can qualify as a tax-free reorganization under Section 368(a)(2)(E) of the Internal Revenue Code. Three conditions must hold:
- Substantially all properties test. After the merger, the surviving target must hold substantially all of its own properties and substantially all of the merger sub’s properties. The IRS ruling guideline in Rev. Proc. 77-37 is at least 90% of the fair market value of net assets and 70% of gross assets.
- Control-for-voting-stock test. Former target shareholders must exchange stock constituting control, defined in §368(c) as at least 80% of total combined voting power and 80% of each other class, for voting stock of the parent.
- The judicial doctrines. Continuity of proprietary interest, continuity of business enterprise, a valid non-tax business purpose, and survival of the step transaction doctrine. Continuity of interest means the target’s shareholders keep a meaningful equity stake in the combined business through the buyer’s stock, rather than simply being cashed out.
The binding constraint is the second test. Because control must be acquired for parent voting stock, non-stock consideration (“boot”) is effectively capped at roughly 20%. That is tighter than a forward triangular merger under §368(a)(2)(D), where continuity of interest is generally satisfied when about 40% of the consideration is buyer stock (Treas. Reg. §1.368-1(e)(2)(v), Example 1), so cash can run to roughly 60%. The forward structure gives up the entity continuity that made the reverse structure attractive in the first place.
How does a two-step merger fit in?
Buyers who want to pay more than about 20% in cash and still get tax-free treatment often add a second merger. Immediately after the reverse triangular merger, the surviving target merges into the buyer or into a second subsidiary, usually an LLC. Under Rev. Rul. 2001-46, the IRS treats the two mergers as one integrated statutory merger under §368(a)(1)(A), which is tested on continuity of interest rather than the 80% voting-stock rule, so the cash component can be much larger.
The trade-off is that the target entity does not survive the second step, and its contracts move to the LLC by operation of law, which can bring anti-assignment clauses back into play. The Salesforce and Slack deal below follows this pattern.
“Two-step merger” also describes a tender offer followed by a back-end merger under DGCL Section 251(h), with no stockholder vote; that back-end merger is usually itself a reverse triangular merger.
| Note: This section is general information, not tax advice. Section 368 analysis is fact-specific, and the step transaction doctrine can unwind a structure that looks clean on paper. Engage qualified tax counsel before signing. |
How Does a Reverse Triangular Merger Compare With Other Deal Structures?
Four structures cover most acquisitions of a whole company, and they differ on three questions: which entity survives, who has to consent, and what happens to the target’s contracts and liabilities.
Table 2. Reverse triangular merger vs. forward triangular merger, stock purchase and asset purchase
| Factor | Reverse triangular | Forward triangular | Stock purchase | Asset purchase |
|---|---|---|---|---|
| What survives | Target | Merger sub | Target | Buyer holds the assets |
| Contracts and licenses | Stay in place; no assignment under Delaware law | Move to the merger sub; consents often required | Stay in place | Assigned individually |
| Target shareholder approval | Majority vote binds holdouts | Majority vote binds holdouts | Each shareholder must sign | Entity-level approval |
| Buyer shareholder approval | Usually not required; exchange rules may apply | Usually not required; exchange rules may apply | Not required | Not required |
| Liabilities | Remain in the target, ring-fenced | Assumed by the merger sub | Remain in the target | Buyer selects what it assumes |
| Default tax treatment | Stock purchase, or tax-free under §368(a)(2)(E) | Tax-free under §368(a)(2)(D) with about 40% buyer stock | Stock purchase | Asset sale; step-up available |
| Best when | Target holds hard-to-transfer contracts, or has a fragmented cap table | Buyer wants the target’s assets in a new entity | Few, cooperative shareholders | Buyer wants to pick assets |
Reverse triangular merger vs. stock purchase: what’s the difference?
These two produce a nearly identical end state. The difference is how you get there. A stock purchase requires every selling shareholder to sign. With four shareholders that’s trivial. With 140 across six financing rounds, a few unreachable ex-employees, and one holdout wanting a premium, it’s a deal-killer. A reverse triangular merger binds all shareholders once the required majority approves; dissenters get appraisal rights. That single fact is why fragmented cap tables almost always end up here.
When does a forward triangular merger make more sense?
The two are mirror images, and the choice comes down to one question: does the target hold anything that can’t be moved? If yes, go reverse. If the buyer’s priority is folding the target’s assets into a new entity and the contract book is clean, forward is simpler. CapLinked covers this in depth in forward mergers vs. reverse triangular mergers, and the wider landscape in 9 types of mergers and acquisitions.
Reverse triangular merger vs. reverse merger (reverse takeover)
A reverse merger, also called a reverse takeover, is a way for a private company to become public without an IPO. The private company merges with a public shell, and its owners end up controlling the listed entity. A reverse triangular merger is an acquisition structure in which a buyer takes over a target and keeps it alive as a subsidiary. The names overlap, and a reverse merger can even run through a triangular structure, but the goals differ: one is about getting a listing, the other about acquiring a company without disturbing its contracts. CapLinked’s guide to reverse mergers covers the going-public version.
What Are the Pros and Cons of a Reverse Triangular Merger?
Every advantage below comes from the same fact, that the target survives intact, and so does every disadvantage.
What are the advantages of a reverse triangular merger?
- Retention of the target entity and its contracts. Agreements, permits, IP licenses, leases and tax IDs stay with the same legal entity. For regulated targets this is often the entire reason the structure was chosen.
- No consent chase for standard anti-assignment clauses. Under Delaware law, anti-assignment clauses generally aren’t triggered (Meso Scale v. Roche), which removes many counterparty negotiations from the critical path.
- Holdout shareholders are bound. Statutory majority approval carries the deal; dissenters receive appraisal rights rather than a blocking position.
- Liability ring-fencing. The target’s pre-closing liabilities stay inside the target entity, so the buyer’s other assets sit behind a corporate wall, subject to the usual exceptions, including successor liability doctrines and any guarantees the parent chooses to give.
- Simplified buyer approval. No buyer shareholder vote and no proxy timeline in most cash deals.
- Flexible consideration. The same structure works for all-cash, all-stock or mixed deals, so the parties can choose taxable or tax-free treatment without changing the legal mechanics.
What are the disadvantages of a reverse triangular merger?
- No asset basis step-up. In the taxable version the buyer inherits the target’s historic asset basis, forgoing future depreciation and amortization benefits.
- All liabilities come along. Unlike an asset purchase, nothing can be left behind, including unknown, contingent and successor liabilities.
- Tight tax-free requirements. The §368(a)(2)(E) 80% control-for-voting-stock test limits cash consideration to roughly 20%, unless the parties add a second merger.
- Change-of-control clauses still apply. Contract continuity isn’t absolute. Any agreement with an express change-of-control provision still requires consent, and those provisions are common in exactly the contracts buyers care most about.
- Anti-assignment protection depends on governing law. Contracts governed by California or New Jersey law may be treated differently from Delaware-law contracts.
- Appraisal exposure. Dissenting target stockholders can ask the court to set the fair value of their shares, which can leave part of the price open after closing.
Reverse Triangular Merger Examples From SEC Filings and Case Law
The four deals below show the main variants: all-cash, two-step, the Delaware anti-assignment case, and a deal held open by antitrust review.
Amazon and One Medical (2022 to 2023), the all-cash version
Why this structure: One Medical held clinical licenses, payer contracts and patient relationships across multiple states, and dissolving the entity would have meant re-papering all of them.
Amazon’s roughly $3.9 billion acquisition of 1Life Healthcare, Inc. (One Medical), including net debt, is a textbook taxable reverse triangular merger. Amazon formed Negroni Merger Sub, Inc., a Delaware corporation and indirect wholly owned subsidiary, on July 18, 2022, two days before the merger agreement was signed, solely to complete the transaction (SEC Form PREM14A).
At closing on February 22, 2023, Merger Sub merged with and into 1Life, Merger Sub’s separate existence ended, and 1Life continued as the surviving corporation and an indirect wholly owned Amazon subsidiary, with its stock delisted from Nasdaq. Consideration was $18.00 in cash per share, so the deal was taxable to 1Life stockholders in the same way as a stock sale.
Salesforce and Slack (2020 to 2021), the two-step reorganization
Why this structure: Salesforce paid a large part of the price in cash and still wanted the deal treated as a tax-free reorganization.
Salesforce’s $27.7 billion acquisition of Slack Technologies used two merger subs, Skyline Strategies I Inc. and Skyline Strategies II LLC. On July 21, 2021, Skyline I merged with and into Slack, with Slack surviving as a wholly owned subsidiary, a standard reverse triangular merger. Immediately afterward, Slack merged into Skyline II, which was renamed Slack Technologies, LLC (SEC Form 8-K).
Each Slack share became 0.0776 Salesforce shares plus $26.79 in cash. At Salesforce’s share price at the time, the cash component was larger than the stock component, well above the roughly 20% that §368(a)(2)(E) allows on its own. The proxy statement said the two mergers, taken together, were intended to qualify as a reorganization under Section 368(a), which is exactly why the second step exists (Form S-4).
Roche and BioVeris (2007), the case that settled the law
Why this structure: Roche wanted BioVeris’s technology rights, and keeping BioVeris alive meant its licenses stayed inside the same legal entity.
Roche acquired BioVeris Corporation in July 2007 through a reverse triangular merger in which a Roche subsidiary, Lili Acquisition Corp., merged into BioVeris. In 2010, Meso Scale Diagnostics sued, arguing the merger breached an anti-assignment clause in a 2003 agreement.
In February 2013, the Court of Chancery granted summary judgment to Roche on that claim, holding that a reverse triangular merger is not an assignment by operation of law where the contracts began and remained the surviving entity’s property (Richards, Layton & Finger).
HPE and Juniper Networks (2024 to 2025), the long regulatory wait
Why this structure: For an all-cash acquisition of a listed company it is the standard form. One stockholder vote binds every holder, and Juniper’s contracts stay with Juniper.
HPE signed its agreement to acquire Juniper Networks on January 9, 2024, at $40.00 per share in cash. Its Delaware subsidiary, Jasmine Acquisition Sub, Inc., was to merge with and into Juniper, with Juniper surviving as a wholly owned subsidiary (SEC Form 8-K).
The U.S. Department of Justice sued to block the deal in January 2025, the parties settled in late June 2025, and the merger closed on July 2, 2025, with about $13.4 billion paid to Juniper stockholders. Juniper kept operating under interim covenants for nearly 18 months, a reminder that diligence findings in a long-dated deal need refreshing before closing.
What Does a Buyer Inherit in a Reverse Triangular Merger?
Every advantage of this structure depends on knowing exactly what you’re inheriting. Because the target survives with all of its liabilities, contracts and regulatory obligations intact, there is no structural escape hatch: you can’t leave a bad lease behind or exclude an unknown claim. What protects the buyer is the quality of the diligence and the contract terms that back it up.
The five areas below carry more weight here than in an asset deal, because each one passes to the buyer automatically. CapLinked’s complete due diligence checklist covers the full request list.
| Area | Why it matters in this structure | What to request |
|---|---|---|
| Material agreements | Contracts stay with the target, so change-of-control clauses and governing law decide which counterparties can object | Agreements above a value threshold, flagged for change-of-control, consent and termination rights |
| Litigation and contingent liabilities | Known and unknown claims stay inside the target | Pending and threatened claims, settlements, regulatory inquiries, warranty and product claims |
| Intellectual property | Gaps in employee and contractor assignments stay with the target | Invention assignment agreements, inbound and outbound licenses, registrations and chain of title |
| Tax attributes | NOLs survive but Section 382 caps their use; past tax exposure survives too | Returns for open years, NOL schedules, prior ownership changes, audit history |
| Permits and licenses | They stay with the entity, but some regulators treat a change of control as a reportable event | Permit list, with notice or approval requirements by regulator |
Table 3. Diligence priorities in a reverse triangular merger
| Note
Representations and warranties insurance now appears in most private-target deals. The ABA’s 2025 Private Target Deal Points Study found that 63% of deals referenced RWI, up from 55% in the 2023 study, and deals in which representations do not survive closing rose from 30% to 41%. |
For IP-heavy targets, IP due diligence deserves its own workstream, and a structured list of due diligence questions helps each workstream ask for the same things in the same format.
Diligence findings feed the protection package in the merger agreement. Representations and warranties allocate the risk of what the seller has or hasn’t disclosed, escrow and indemnities give the buyer a source of recovery, and representations and warranties insurance shifts part of that risk to an insurer.
How CapLinked Supports Reverse Triangular Merger Due Diligence
This structure puts three demands on the data room: access that differs by bidder, a record of what each party saw and asked, and control over documents once they leave the room.
- One permission group per bidder. In a CapLinked virtual data room, access is granted to permission groups, with view, download and upload rights set by folder. One group per bidder keeps a competing buyer out of another’s materials, and access can be set to expire on a chosen date.
- Confidentiality agreements on entry. You can require guests to accept a confidentiality agreement before they enter the workspace, assign different agreements to different parties, and keep the signed copy in the workspace.
- Control after download. FileProtect converts protected files to PDF, applies watermarks carrying the viewer’s name, email and IP address, blocks printing and re-sharing, and lets you revoke access to a downloaded file when a bidder drops out.
- Q&A with an audit record. EZ Q&A routes each question to a named administrator, promotes answers to a shared FAQ, and exports a full Q&A report for the post-closing file.
- Engagement by group and by document. The Activity Tracker shows logins, views, downloads and time spent per document for each permission group, with CSV export. It tells you what was opened and for how long, not why.
- AI Document Summary and AI Executive Report. AI Document Summary condenses a long document in roughly 30 to 60 seconds and can flag contradictory figures across sections; the AI Executive Report turns room activity into a PDF for client updates.
- Redaction on Enterprise. The Enterprise plan adds in-platform PDF editing and redaction, with a preview of exactly what non-administrators will see.
CapLinked is SOC 2 certified, encrypts data at rest with 256-bit AES and in transit with TLS, and runs on AWS infrastructure that is itself SOC 2 and ISO 27001 certified; the security overview lists the full set of controls for secure document sharing.
As of October 2026, the Team plan is $399 per month with no long-term contract and includes watermarking, FileProtect, EZ Q&A, the Activity Tracker and OCR search. Enterprise is quoted individually, and CapLinked matches comparable written quotes; current pricing shows what each plan includes.
Before committing to this structure, settle three questions: which law governs the target’s key contracts, what share of the price will be cash, and how much of the target’s history diligence can realistically cover before signing. If the answers point to a reverse triangular merger, the data room is where you find out what you are inheriting.
| Set up your deal workspace before diligence begins, or talk to CapLinked about a multi-deal Enterprise setup. |
Reverse Triangular Merger FAQs
Is a reverse subsidiary merger the same as a reverse triangular merger?
Yes. “Reverse subsidiary merger” is the term the IRS uses in rulings such as Rev. Rul. 2001-46. Both describe a buyer’s subsidiary merging into the target, with the target surviving as the buyer’s wholly owned subsidiary.
What is a merger sub?
A merger sub is a shell company a buyer forms only to complete an acquisition. It has no operations, merges with the target at closing, and in a reverse triangular merger it ceases to exist while the target survives.
Is a reverse triangular merger taxable?
It depends on the consideration. An all-cash deal is taxed like a stock purchase, so target shareholders recognize gain or loss. It can be tax-free under IRC §368(a)(2)(E) if at least 80% of target stock is exchanged for buyer voting stock.
Does a reverse triangular merger trigger anti-assignment clauses?
Generally no, under Delaware law. In Meso Scale v. Roche (2013), the Court of Chancery held that it is not an assignment by operation of law. Change-of-control clauses still apply, and some other states’ courts have ruled differently.
Who needs to approve a reverse triangular merger?
The target’s board and a majority of its outstanding shares, unless a tender offer under DGCL Section 251(h) replaces the vote. The buyer approves as the merger sub’s sole stockholder. Antitrust and sector regulators may also need to clear it.
What happens to the target’s liabilities?
They stay with the target, which survives as the buyer’s subsidiary. Unlike an asset purchase, nothing is left behind. The buyer’s other assets generally sit outside the target, subject to successor liability doctrines and any parent guarantees.
Does the target keep its name and tax ID after a reverse triangular merger?
Generally yes. The target is the same legal entity after closing, so it keeps its employer identification number, and its name unless the merger agreement amends its charter. Its shares are simply held by the buyer.