Key Takeaways
- Merger arbitrage captures the gap between a target’s share price after a deal is announced and the price the acquirer agreed to pay
- The strategy depends on the deal closing. A deal that breaks is the loss case
- That gap exists because completion is uncertain, and it narrows to zero at close
- Cash deals mean buying the target. Stock deals mean buying the target and shorting the acquirer
- Payoffs are asymmetric: many small gains against occasional sharp losses
- A wide spread signals doubt about completion, not a better opportunity
Table of Contents
ToggleMerger and arbitrage are both common business terms. A merger combines two companies. Arbitrage means buying and selling the same asset in different markets to profit from a price difference. Put together, merger arbitrage means something more specific than either word suggests.
It is one of the oldest event-driven strategies in the hedge fund universe, and its logic is simple enough to state in a sentence. Executing it well is not, because the whole return depends on judging one thing correctly: whether the deal will actually close.
This guide covers how the merge arbitrage works, the difference between cash and stock deals, how arbitrageurs assess completion risk, where the strategy loses money, and worked examples from deals announced in 2025 and 2026. But first, the basics.
What Is Merger Arbitrage?
Merger arbitrage is an investment strategy that profits from the successful completion of an announced M&A deal. Investors who run it are called arbitrageurs.
When a deal is announced, the target’s share price jumps toward the offer price but usually stops short of it. That remaining gap is the spread, and it exists because the market is not certain the deal will complete. Regulators can block it, shareholders can vote it down, financing can fall through, or the acquirer can walk away.
The arbitrageur takes the other side of that doubt. Buy the target below the offer price, hold until the deal closes, and collect the difference. If the deal completes, the spread goes to zero and the position pays out.
The strategy is largely uncorrelated with the broader market, because what drives the return is deal completion rather than share price direction. That is what makes it attractive to institutions looking for returns that do not move with equities.
How Does the Merger Arbitrage Spread Work?
The spread is the difference between the price the acquirer agreed to pay and the price the target trades at today. It narrows as completion becomes more certain and reaches zero when the deal closes.
It is standard practice for the acquiring company to offer a premium for the target’s stock, so the announcement almost always lifts the target’s share price. An investor who already held shares captures that jump on the day. An investor buying afterwards is buying the spread that remains.
A worked example
In late 2025 GSK agreed to acquire the oncology company Nuvalent for $124 per share in cash, with completion expected in the third quarter of 2026. Suppose that while the deal awaits clearance the target trades at $120.
|
Input |
Figure |
|---|---|
|
Offer price |
$124 per share |
|
Market price today |
$120 per share |
|
Gross spread |
$4 per share, or 3.3% |
|
Expected time to close |
About 90 days |
|
Approximate annualized return |
About 13% |
The last row is the one that matters. A 3.3% gross spread is unremarkable by itself, but earned in 90 days it annualizes to roughly 13%. Stretch that same 3.3% across an 18 month regulatory review and it annualizes to barely 2%, which is worse than leaving the money in cash once break risk is priced in.
Ingredion’s cash bid for the UK ingredients group Tate & Lyle, not expected to close until the second half of 2027, is a live illustration. A reasonable gross spread stretched over a long timeline stops being a reasonable return.
Cash Deals vs Stock Deals
The two structures require different trades. In a cash deal the arbitrageur buys the target. In a stock deal the arbitrageur buys the target and shorts the acquirer, because the payout is denominated in the acquirer’s shares rather than in dollars.
|
Cash deal |
Stock deal |
|
|---|---|---|
|
What the acquirer pays |
A fixed dollar amount per share |
A fixed number of its own shares per target share |
|
The trade |
Long the target only |
Long the target, short the acquirer at the exchange ratio |
|
Why the hedge |
Not needed. The payout is fixed |
The payout moves with the acquirer’s share price, so the short locks the ratio |
|
Main exposure |
Deal completion |
Deal completion, plus borrow cost and availability on the short |
A collar sits between the two. It fixes the exchange ratio only while the acquirer’s shares trade inside an agreed band, and floats outside it, which changes the hedge the arbitrageur has to run.
|
The deals arbitrageurs trade run on secure document exchange between the parties. |
How Do Arbitrageurs Assess Deal Risk?
Arbitrageurs estimate the probability that a deal completes, then decide whether the spread pays them enough for that risk. The merger agreement is the primary document, and the termination fee inside it signals how committed the acquirer is.
Four hurdles decide most outcomes.
- Antitrust and regulatory approval. The largest single cause of broken deals, and the hardest to handicap. Reviews can run across the US, the EU, the UK and China, and any one of them can impose conditions that kill the economics
- Shareholder approval. Usually procedural, occasionally not, particularly when a large holder objects publicly or a proxy adviser recommends against
- Financing. Whether the acquirer’s funding is committed and what happens to it if credit conditions move
- Timeline. Not a break risk but a return risk. Every month of delay reduces the annualized return on a fixed spread
Deal structure matters too. A management buyout or a friendly strategic acquisition carries different completion odds from a contested bid, and the type of transaction shapes which regulator takes an interest.
Hostility and the degree of resistance
How amenable the target is to the deal is a useful signal. The greater the target’s resistance, the harder the process and the lower the odds of completion. A board that has unanimously recommended a deal to its shareholders is a materially different proposition from one fighting a hostile approach.
Active and passive arbitrage
Active arbitrage is when an arbitrageur holds enough of the target’s stock to influence the outcome, typically by voting the position or pressing publicly for better terms. Passive arbitrage is a position too small to sway the transaction. Most arbitrageurs are passive, and the distinction matters mainly for disclosure obligations and for how a large holder’s position is read by the market.
What Are the Risks of Merger Arbitrage?
The payoff is asymmetric. Successful deals return a few percent each, while a broken deal sends the target back toward its pre-announcement price and takes the whole premium with it.
Mitchell and Pulvino’s 2001 study in the Journal of Finance characterized the return profile as similar to writing uncovered index put options: steady small premiums collected most of the time, with occasional severe losses. The trader’s version of the same idea is picking up pennies in front of a bulldozer.
Two 2026 deals show what the loss case looks like.
Getty Images agreed to acquire Shutterstock in January 2025, with a cash election of $28.85 per share among the options offered to Shutterstock holders. Reuters reported that Getty terminated the deal on June 30, 2026 over UK regulatory conditions. Shutterstock fell 29% to $9.95.
In January 2026 the Federal Trade Commission won a preliminary injunction against Edwards Lifesciences’ $945 million acquisition of JenaValve Technology, and the parties terminated rather than litigate.
A third risk is correlation. The strategy is described as market neutral, and mostly behaves that way, but in severe dislocations such as 2008 and March 2020 spreads widen across every position at once as risk appetite collapses. The left tail arrives when everything else is already going wrong.
How Funds Boost Returns
Individual spreads are small, so funds use two levers: leverage and diversification.
Leverage multiplies a low single-digit spread into a return worth pursuing. It also multiplies the loss when a deal breaks, which is why leverage and diversification are used together rather than separately.
Diversification means running many positions at once across sectors, deal sizes and regulatory jurisdictions, so no single break dominates the portfolio. A fund holding 40 deals absorbs one failure. An investor holding three does not.
This is the practical reason merger arbitrage is mostly institutional. Access to leverage, the research capacity to handicap regulatory outcomes across jurisdictions, and enough capital to hold a diversified book are all difficult individually. AllianceBernstein noted that as more arbitrage capital chases a favorable M&A environment, spreads compress and the return for bearing completion risk shrinks.
Merger Arbitrage Examples
|
Deal |
Setup |
Outcome for the arbitrageur |
|---|---|---|
|
GSK and Nuvalent, 2025 |
Cash deal at $124 per share, target trading near $120 |
A 3.3% gross spread, roughly 13% annualized over an expected 90 day close |
|
Ingredion and Tate & Lyle, 2026 |
Cash bid, completion not expected until the second half of 2027 |
A workable gross spread stretched thin by a long timeline |
|
Getty Images and Shutterstock |
Announced January 2025, terminated June 2026 over UK regulatory conditions |
Shutterstock fell 29% to $9.95 on termination. The break case |
|
Edwards Lifesciences and JenaValve |
$945 million deal, FTC won a preliminary injunction in January 2026 |
Terminated. Antitrust remains the most common cause of a break |
Two closed, two did not, which is roughly the shape of the job. The returns on the first two are earned by correctly judging that the last two were the exceptions.
Why Deal Certainty Matters to Arbitrageurs
Everything above depends on announced deals actually closing. That makes execution quality relevant to arbitrageurs even though they have no part in it: delays extend timelines and compress annualized returns, and surprises surfacing late in due diligence are a common route to renegotiation or termination.
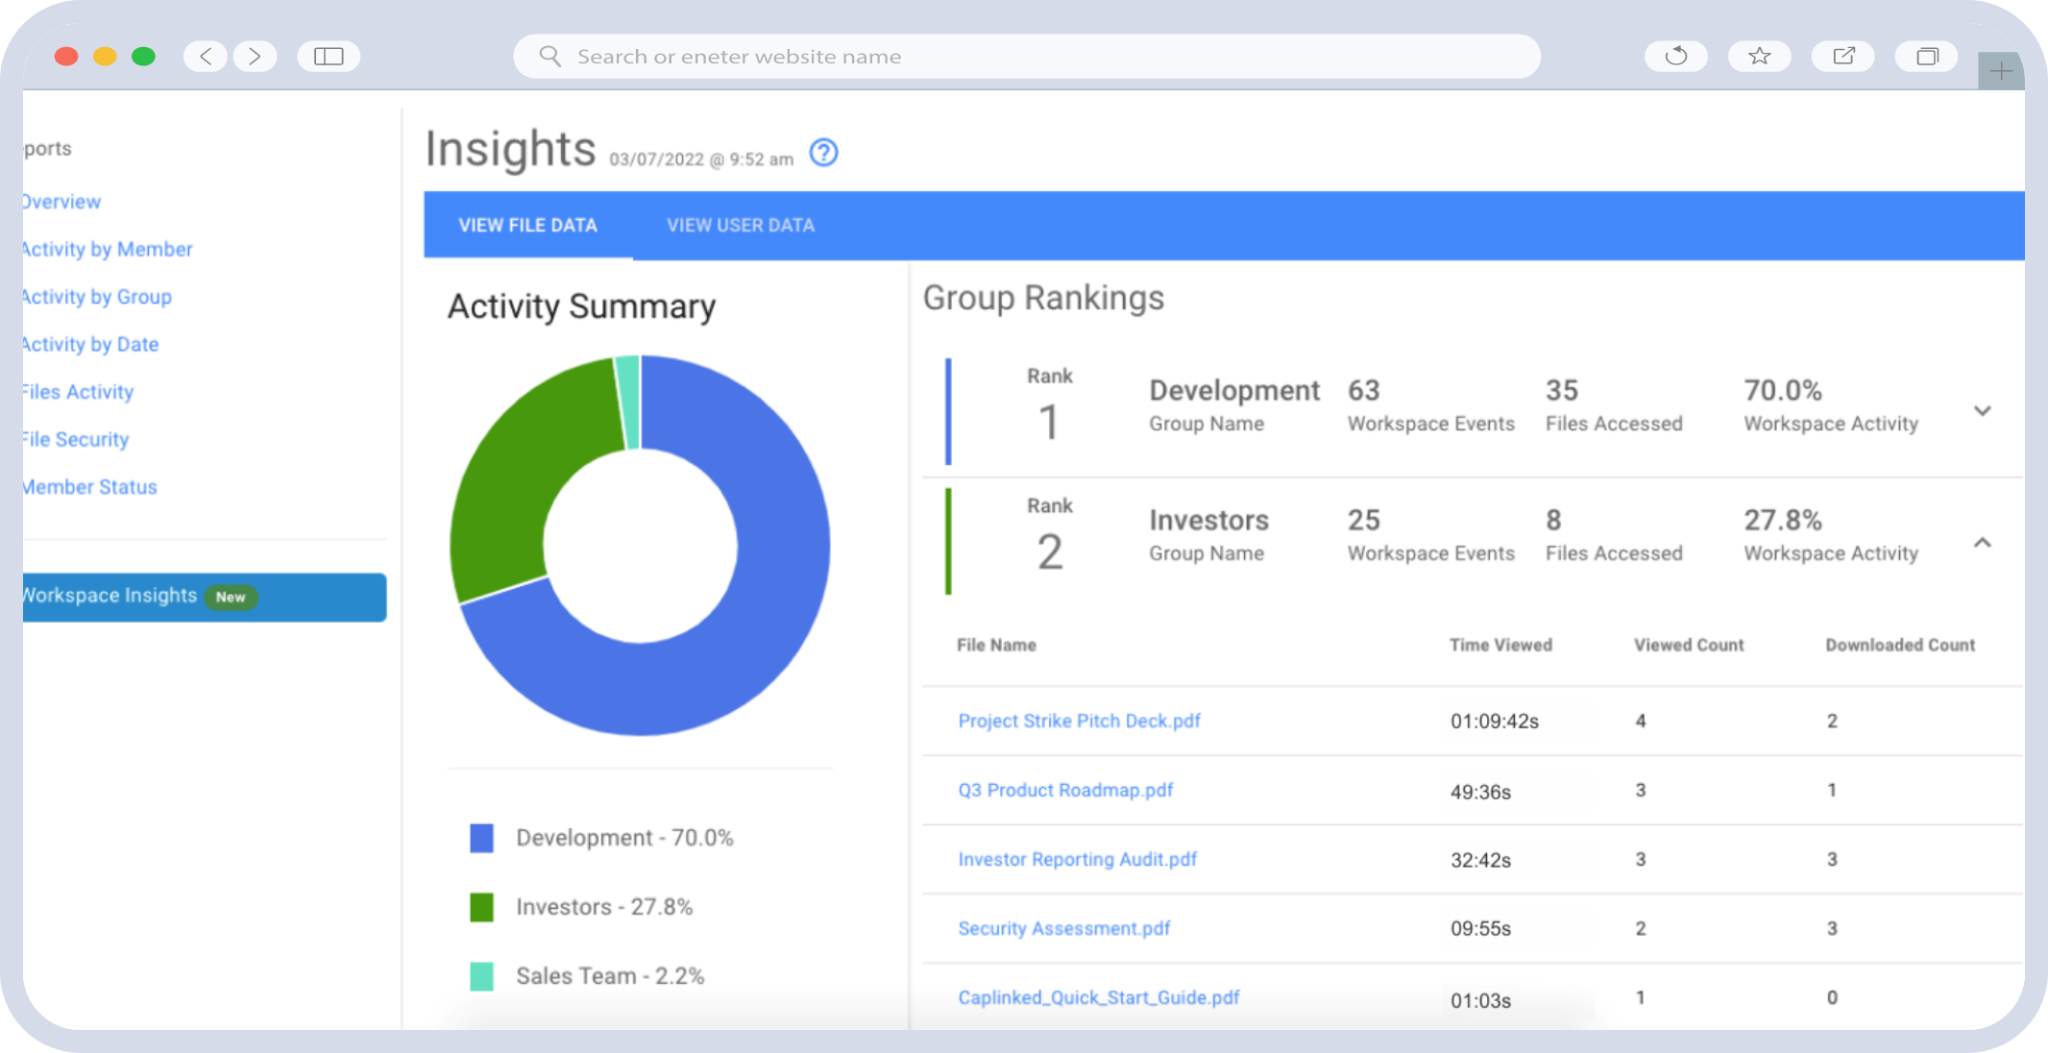
The underlying transactions run in a virtual data room (VDR), a controlled online workspace where the parties, their lawyers and their accountants exchange the confidential documents a deal requires.
CapLinked is one such platform. Workspaces deploy in minutes with no plugin on either side, EZ Q&A routes diligence questions to the right person and builds an FAQ so the same question is answered once, and permission groups control who sees which folder.
Security is 256-bit encryption at rest and in transit on AWS infrastructure, with SOC 2 compliance and FileProtect digital rights management included on the entry plan rather than reserved for the top tier. The security page lists the full certification set, and the Team plan is published at $399 per month.
To be clear about the boundary: a data room is deal execution infrastructure, not a trading tool. Nothing here helps an arbitrageur pick a position. It helps the parties on either side of the deal get to a close, which is the event the position depends on.
|
Running the deal rather than trading it? |
Merger Arbitrage FAQ
What is merger arbitrage?
An event-driven investment strategy that profits when an announced merger or acquisition completes. The arbitrageur buys the target company below the agreed offer price and captures the difference when the deal closes.
What is the difference between merger arbitrage and risk arbitrage?
Merger arbitrage and risk arbitrage are the same strategy. Risk arbitrage is the older term and emphasizes that the position carries completion risk rather than being a true riskless arbitrage.
How is the merger arbitrage spread calculated?
Subtract the target’s current market price from the agreed offer price. A target trading at $120 against a $124 cash offer has a $4 spread, or 3.3%. That figure is then annualized against the expected time to close.
What happens if a merger deal fails?
The target’s share price usually falls back toward where it traded before the announcement, and the arbitrageur takes a loss that can exceed the gains from several successful deals. Deal breaks are the strategy’s main risk.
Is merger arbitrage low risk?
It is low volatility rather than low risk. Returns are small and steady across many completed deals, with occasional sharp losses when one breaks. Academic work characterizes the payoff as similar to writing put options.
Can individual investors do merger arbitrage?
It is predominantly institutional, because the strategy needs leverage, diversification across many simultaneous deals, and the research capacity to handicap regulatory outcomes. Merger arbitrage funds and ETFs offer indirect exposure.