Key Takeaways
- Precedent transaction analysis values a company using the multiples buyers actually paid in comparable M&A deals, also called transaction comps.
- The method sits alongside the discounted cash flow model and comparable company analysis as one of the three core ways to value a company.
- Because it draws on real takeover prices, precedent transaction analysis captures a control premium that trading comps leave out, so it often sets the high end of a valuation range.
- The workflow runs in clear steps: screen comparable deals, pull transaction values, calculate multiples such as EV/EBITDA, then apply the median to the target’s metrics.
- Output quality depends on comp quality, so recency, industry fit, deal size, and buyer type all matter when you screen.
- Public deal data is often thin and dated, which is why analysts pair this method with a DCF and trading comps rather than relying on it alone.
- The financial detail behind transaction comps is exchanged during due diligence, usually inside a secure virtual data room.
Table of Contents
TogglePrecedent transaction analysis values a company using the prices buyers paid to acquire similar businesses. Because those prices come from deals that actually closed, the method shows what an acquirer was willing to pay for control, not just where a stock trades.
That grounding in real deals is the method’s strength and its limit. The multiples are concrete, but usable deals are not always recent, public, or truly comparable, so analysts rarely lean on it alone.
This guide covers what the method measures, how to run it step by step, how to pick comparable deals, and where the control premium comes from, with a short worked example and a side-by-side look at trading comps.
What Is Precedent Transaction Analysis?
Put simply, the method estimates a company’s value by benchmarking it against the purchase prices of recent, comparable acquisitions. Each comparable deal gives a multiple, such as enterprise value to EBITDA, and those multiples are applied to the target to imply a value range.
It goes by several names that mean the same thing:
- Merger and acquisition (M&A) transaction comps
- comparable transactions
- deal comps
It is one of the three core valuation methods, alongside comparable company analysis and the discounted cash flow (DCF) model. What sets it apart is the source of its numbers. Comparable company analysis reads value from how similar public companies trade, while precedent transaction analysis reads value from what buyers paid to own a business outright, which includes a premium for control.
Why It Matters in M&A Valuation
Because its multiples come from completed deals, precedent transaction analysis answers a question the other methods cannot: what has someone actually paid to own a business like this one?
A discounted cash flow model values a company on its own projected cash flows. Comparable company analysis values it against how peers trade in the public market. Precedent transaction analysis adds the missing reference point, the prices buyers have paid in real acquisitions, control premium and expected synergies included.
That is why the method often sets the upper end of a valuation range. A buyer taking control pays for more than a minority stake in the open market, so transaction multiples usually run above trading multiples. Deal teams use the output to sanity-check an offer, frame negotiations, and show a board what comparable businesses have commanded.
The analysts who build these analyses typically sit in investment banking, corporate development, and private equity, and they run the numbers most often during the due diligence phase of a live deal.
How to Do Precedent Transaction Analysis (Step by Step)
The workflow is the same whether you are valuing a private target or pressure-testing a public one. Five steps take you from a universe of deals to an implied value range.
- Screen for comparable deals. Build a list of recent acquisitions of similar businesses. Filter on industry, business model, size, geography, timing, and buyer type until the set genuinely resembles the target.
- Gather each deal’s terms. Pull the transaction value and the target’s financials at the time, usually revenue and EBITDA, from filings, press releases, and deal databases.
- Calculate the multiples. For each deal, divide enterprise value by a financial metric to get multiples such as EV/EBITDA and EV/revenue, then discard outliers that distort the set.
- Apply the range to your target. Take the median or mean multiple from the clean set and apply it to the target’s own revenue or EBITDA to imply a valuation.
- Derive a value range. Present a low-to-high range rather than a single number, and read it alongside a DCF and trading comps before drawing a conclusion.
Selecting Comparable Transactions
Every number that follows depends on this step. Weak comparables produce a confident-looking range built on the wrong deals.
| Screening criterion | What to look for | Why it matters |
|---|---|---|
| Industry and business model | Same sector, similar revenue drivers and margins | Multiples only transfer between genuinely similar economics |
| Deal size | Transactions in a comparable value band | A mega-merger multiple rarely fits a lower-middle-market target |
| Timing | Recent deals struck in similar market conditions | Multiples drift with credit costs and sector sentiment |
| Buyer type | Strategic vs financial (PE) acquirers | Strategics pay for synergies; sponsors price to a return |
Aim for a tight set of close comparables over a long list of loose ones. A handful of well-matched acquisitions of similar businesses beats 20 rough approximations.
The Control Premium
This premium is the single biggest reason transaction comps and trading comps disagree.
A control premium is the extra amount an acquirer pays above a company’s standalone market value to gain control of it. Owning a business outright means controlling its board, its strategy, and its cash flows, and it lets the buyer capture synergies that a passive shareholder never sees.
Because completed acquisitions include this premium, the multiples they produce sit above the trading multiples of comparable public companies. That gap is exactly what precedent transaction analysis captures and comparable company analysis does not.
The size of the premium is not fixed. It shifts with the buyer’s motivation, the level of competition for the target, and the synergies on offer, so it should be read as a deal-specific figure rather than a standard mark-up.
Precedent Transactions vs. Trading Comps
Both are multiples-based, so it is easy to treat them as interchangeable. They answer different questions.
| Precedent transactions | Trading comps | |
|---|---|---|
| What it measures | Prices paid in completed acquisitions | How similar public companies trade today |
| Control premium | Included | Excluded |
| Best used for | Gauging what an acquirer might pay | Gauging standalone market value |
| Data source | Deal filings, press releases, databases | Live public market prices |
| Main limitation | Deals can be dated or scarce | Reflects minority, not control, value |
In practice, analysts run both. Trading comps show where the market values the business as it stands; precedent transactions show what changing hands has historically cost.
A worked example
A simple example shows how the steps produce a number. Suppose you are valuing a target with $50 million in EBITDA and you find three recent, comparable acquisitions. For illustration, their multiples came in as follows:
| Comparable deal | Enterprise value | Target EBITDA | EV/EBITDA |
|---|---|---|---|
| Deal A | $480M | $40M | 12.0x |
| Deal B | $550M | $50M | 11.0x |
| Deal C | $650M | $50M | 13.0x |
The median of these multiples is 12.0x. Applying it to the target’s $50 million in EBITDA implies an enterprise value of about $600 million. A real analysis would show a range, say 11.0x to 13.0x, putting the target between roughly $550 million and $650 million before any deal-specific adjustments.
Treat these figures as illustrative. Real multiples depend entirely on the comparable deals you can find and defend.
Limitations of the Method
For all its grounding in real deals, the method carries real constraints, and good analysts flag them up front.
- Thin data: genuinely comparable deals are often scarce, especially for private or niche targets
- Disclosure gaps: private deal terms may never be public, so multiples rest on incomplete information
- Stale comps: deals struck under different credit or market conditions can misprice today’s target
- No two deals alike: every target has quirks, so even close comparables need judgment, not mechanical copying
- Backward-looking: the method reflects what buyers paid before, which may not hold in a changed market
None of this rules the method out. It is why precedent transaction analysis is read alongside a DCF and trading comps rather than trusted on its own.
Where Transaction Comp Data Comes From
One practical question sits underneath every step above: where does the deal data actually come from?
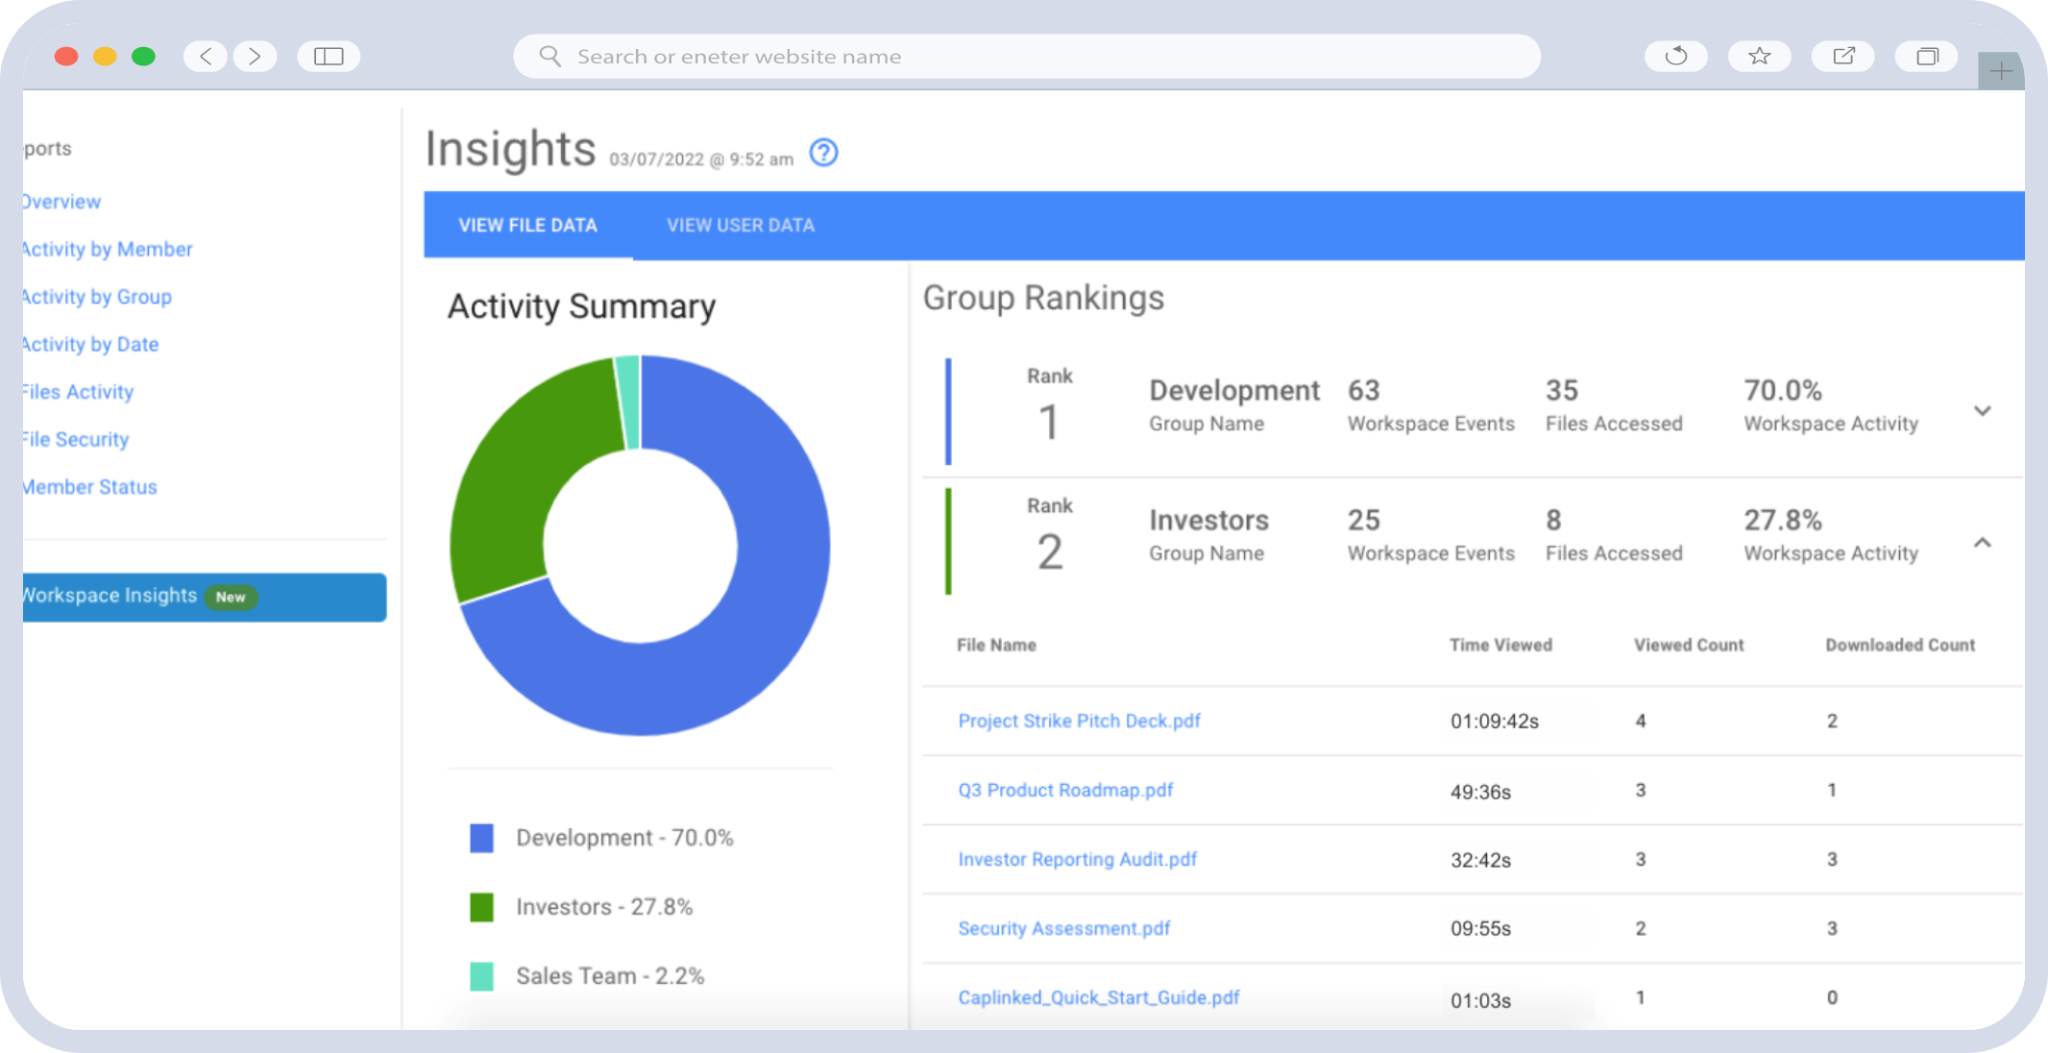
Much of it comes from public filings and deal databases. The detailed financials behind a trusted multiple, the ones exchanged when a specific deal is live, move through due diligence. During that phase, both sides share sensitive documents in a virtual data room (VDR), a controlled space for storing, sharing, and reviewing deal materials with a full record of who accessed what.
CapLinked provides secure virtual data rooms for M&A and other transactions, with granular permissions, activity tracking, and document protection built for sensitive deal files. If you are running diligence on a live transaction, you can start a free trial and set up a room in minutes.
Precedent Transaction Analysis FAQ
What is precedent transaction analysis in simple terms?
It values a company using the prices buyers paid for similar businesses in past acquisitions. Each comparable deal gives a multiple, and applying those multiples to the target implies a value range.
How is it different from comparable company analysis?
Comparable company analysis reads value from how similar public companies trade today. Precedent transaction analysis reads value from completed acquisitions, so it includes the control premium a buyer pays and usually produces higher multiples.
What is a control premium?
It is the extra amount an acquirer pays above a company’s standalone market value to take control. It reflects command of the business plus expected synergies, and it is why transaction multiples exceed trading multiples.
Which multiples are used most often?
Enterprise-value multiples are standard, most commonly EV/EBITDA and EV/revenue. Analysts pick the metric that best reflects the target’s economics and that the comparable deals disclose consistently.
Why is it called the least used of the three methods?
Usable comparable deals are often scarce, dated, or privately disclosed. That thin data makes it less reliable on its own, so teams treat it as a cross-check against a DCF and trading comps.
Is precedent transaction analysis financial advice?
No. It is an educational overview of a valuation method. Applying it to a real transaction calls for professional judgment and advisers who can verify each comparable deal and its terms.