Key Takeaways
- An oil and gas virtual data room is a permissioned workspace built for the document volume an energy deal generates
- Energy diligence spans reserves, title, environmental liability and operating agreements, each with its own reviewer
- Scope access by discipline, so engineers, land teams and consultants reach only their own material
- Structure folders by reviewer discipline rather than by document type
- Large reserve reports and seismic files make upload handling a practical requirement, not a footnote
- The audit trail matters more here, because title defects can surface long after close
- Deal count is falling while deal value rises, so each transaction faces more scrutiny
Table of Contents
ToggleAn oil and gas virtual data room is a permissioned online workspace for sharing the documents an energy transaction requires: reserve reports, title and lease files, environmental assessments and operating agreements. What separates it from a general data room is the reviewer structure, since engineers, land teams, environmental consultants and lenders each need a different slice of the same property set.
The requirement comes from what is being valued. A buyer in most sectors is valuing a business. A buyer here is valuing hydrocarbons nobody has seen, under land whose ownership sits in decades of county filings, with cleanup obligations that outlive the production.
That combination decides what the room has to do. The sections below cover why energy deals generate the volume they do, which capabilities matter, how to structure the folders, and what to ask a provider.
Where the Market Stands
US upstream M&A closed 2025 at $65 billion, with the fourth quarter contributing $23.5 billion, according to Enverus Intelligence Research. The first quarter of 2026 then reached $38 billion, the highest quarterly total in two years.
Read alongside that headline number is a second one that changes its meaning. Only eight deals above $100 million were recorded in that quarter, tying a post-2020 low. The market is not getting busier. It is concentrating into fewer, larger transactions, one of which, the roughly $25 billion Devon and Coterra merger, accounted for about two thirds of the quarter by itself.
Enverus found that through 2025 investors rewarded deals with overlapping operations and credible cost synergies, while penalizing transactions that looked like scale for scale’s sake. For a deal team, that raises the standard of proof. A buyer now defends its diligence to its own shareholders, not only to its board.
| Did You Know
International upstream M&A totaled just $18 billion in 2025, flat year over year and well below the $60 billion historical annual average, per Enverus. Availability of transactable high-quality resources, rather than buyer appetite, is the binding constraint. |
Why Oil and Gas Companies Merge
Consolidation dominates the current market, and the reasons behind it shape what diligence has to test.
- Inventory scarcity. High-quality drilling inventory from private sellers is increasingly hard to buy, which pushes public operators toward corporate consolidation instead of asset packages
- Operational overlap. Acquiring adjacent acreage lets a buyer use existing infrastructure and crews, which is the synergy case investors currently reward
- Portfolio reshaping. Companies divest non-core positions to fund core-area buying, keeping divestiture activity high even in slow quarters
Energy transition positioning. Moves into renewable energy and reduced hydrocarbon exposure continue to influence which assets change hands, alongside evolving regulation and tax treatment.
Why Energy Deals Need a Purpose-Built Data Room
Four areas separate energy diligence from other sectors. Each has its own specialist reviewer and its own document set, which is what drives the requirements in the next section.
Reserves and production data
Reserve reports estimate what remains recoverable, and they are engineering judgments rather than measurements. A buyer examines the assumptions behind the estimate: decline curves, recovery factors, the price deck used, and whether reserves are classified as proved developed, proved undeveloped or probable.
The gap between categories matters more than the headline number. Proved undeveloped reserves require future capital to become production, and a seller with a large undeveloped component is selling a plan alongside an asset.
Title and land records
Mineral and leasehold interests are recorded in county filings accumulated over decades, sometimes with fractional interests split across dozens of heirs. Title examination confirms the seller owns what it is selling and identifies defects: gaps in the chain, unreleased liens, expired leases, or depth severances.
This is the most common source of price adjustment in upstream deals. Defects are usually curable, and curing them takes time the deal timeline may not have.
Environmental and abandonment liability
Plugging and abandonment obligations attach to wells and transfer with the asset. So does contamination liability, which can predate the seller’s ownership. A buyer reviews environmental assessments, spill history, regulatory notices and the estimated cost of eventual well retirement.
Idle and orphaned wells deserve particular attention, because a well producing nothing still carries the full cost of retiring it.
Contracts and joint operating agreements
Shared properties run on joint operating agreements governing who operates, how costs are allocated and what consent rights partners hold. Marketing, gathering, processing and transportation contracts determine what the production actually realizes. Preferential rights and consent-to-assign provisions can delay or block a transfer entirely, which is why they get read early rather than late. These sit alongside the wider asset categories any acquirer reviews.
| Common Mistake
Enverus reports that in 2025 public equity investors “rewarded deals that were clearly additive with overlapping operations, credible cost synergies and durable inventory quality but penalized transactions that looked like scale for scale’s sake”, in its full-year review. A thin synergy case is now a market risk, not just a board conversation. |
What the Document Volume Actually Looks Like
Knowing that the oil and gas industry is among the largest, most globalized and most complex means any deal-making in the space has a lot of moving parts. Even the smallest assets or data points can greatly affect the value of the transaction.
The practical problem is volume and structure. A single producing property generates lease documents, division orders, title opinions, regulatory filings, production records, environmental assessments and operating agreements. Multiply that across hundreds of wells and several counties, then hand it to a buyer running a fixed diligence window.
Three areas need particular care because each carries its own set of downstream issues:
- Quantifying the barrels that remain recoverable, and on what assumptions
- The financial position of royalty holders, including any disputed interests
- Future royalty and revenue payments, covering joint interest billing and working interest allocations
Reviewers also arrive with different mandates. Reserve engineers need production data and reserve reports. Land teams need title and lease files. Environmental consultants need assessments and spill records. Each should reach their own material without seeing the rest, which is a permissions problem before it is a technology one, and one worth designing with access control planned in advance.
What an Oil and Gas Virtual Data Room Needs to Do
Seven capabilities carry the weight in an energy transaction. Our wider guide to why modern M&A requires a data room covers the general case; what follows is what changes for oil and gas, and why.
Scope access by reviewer discipline
Energy diligence is run by specialists who need different materials and have no reason to see each other’s. A reserve engineer needs production history and decline curves. A landman needs title opinions and division orders. An environmental consultant needs site assessments and spill records. A lender needs the reserve report and the hedge book.
Group-based permissions handle this in one structure. Each discipline reaches its own folders, and nothing is duplicated into separate rooms. On a divestiture with several bidders, party groups sit alongside discipline groups so competitors stay sealed from each other while their engineers work the same well data.
The alternative, which is how these rooms often get built, is one folder set opened to everyone with an NDA. That works until a bidder withdraws having seen your full acreage economics.
Handle large technical files without failing
Seismic interpretation, well logs and reserve reports are large. A room with a per-file ceiling or slow upload becomes a bottleneck at the moment a deal can least afford one, and the workaround is always the same: someone emails a link to a personal cloud drive, and the controls stop applying.
Ask about per-file limits and total capacity before signing rather than discovering them the week the technical data lands.
Search inside scanned documents
Title records are often decades of scanned county filings. Filename search is useless against them, because the filename says nothing about which tract or which depth interval a document covers.
Optical character recognition makes the contents searchable, so a reviewer looking for a specific lessor name or a depth severance finds it in seconds rather than opening files in sequence. On a property set spanning hundreds of wells, this is the difference between a two-week title review and a six-week one.
Route questions to the right specialist
On a large property set the same question about a lease term arrives from several reviewers at once. Structured Q&A routes each query to whoever can actually answer it, keeps the thread attached to the document it concerns, and publishes recurring answers so the next reviewer finds them without asking.
Without it, the seller’s land manager answers the same question four times, sometimes differently, and nobody can reconstruct afterward what was said to whom.
Control versions as data is revised
Reserve reports get revised. Title opinions get supplemented as defects are cured. Production data updates monthly while a deal runs. Every one of those changes has to reach every reviewer at once, because a buyer valuing off a superseded reserve report is a dispute waiting to happen.
Version history also answers the question that surfaces later: what did the reserve report say in March, before the revision. That is not a filing convenience. It is the record behind a valuation.
Keep control after documents are downloaded
Most bidders in an energy process will not proceed, and each one leaves holding whatever it downloaded. Rights management restricts printing and forwarding, and allows access to a downloaded file to be revoked once a party exits.
The exposure here is specific. Acreage economics, decline assumptions and operating costs in the hands of a competitor who also operates in your basin is a competitive problem long after the deal question is settled.
Produce a defensible access record
Title defects surface after close. Reserve estimates get challenged. When either happens, audit trails showing who saw what establish what was disclosed and when, which matters more in energy than in most sectors because so much of the record predates everyone in the room.
Treat the log as a record rather than a detection system. It shows which reviewer opened which document. It cannot tell you whether they understood it, or what they concluded.
| Capability | The energy-specific problem it solves |
|---|---|
| Discipline-scoped access | Engineers, land, environmental and lenders need different slices of the same property set |
| Large file handling | Seismic and well log files break rooms built for contracts |
| Search inside documents | Decades of scanned title records are unsearchable by filename |
| Threaded Q&A | One lease question arrives from four reviewers on a large property set |
| Version control | Reserve reports and title opinions get revised mid-process |
| Control after download | Most bidders withdraw holding your acreage economics |
| Audit record | Title defects and reserve challenges surface after close |
How to Structure an Oil and Gas Data Room
Structure the room around who is reviewing rather than around what the document is. A title opinion, a production record and an environmental assessment for the same property go to three different specialists, and filing them together forces each one to wade through the other two.
| Folder | Contents | Primary reviewer |
|---|---|---|
| Reserves and production | Reserve reports, decline curves, production history, price decks | Reserve engineers |
| Land and title | Leases, division orders, title opinions, assignments, depth severances | Land and legal teams |
| Environmental and regulatory | Site assessments, spill history, regulatory notices, abandonment estimates | Environmental consultants |
| Contracts | Joint operating agreements, marketing, gathering, processing, transportation | Commercial and legal |
| Financial | Revenue statements, joint interest billing, working interest allocations | Financial diligence |
| Corporate | Entity records, permits, litigation, insurance | Deal counsel |
Set permissions at folder level once the structure exists, then add reviewer groups against it. Building the structure after inviting people is how access ends up assigned document by document, which stops being auditable within about two weeks on a deal this size.
How to Choose a Provider for Energy Deals
Most provider comparisons are written around generic criteria. Five questions matter specifically for oil and gas.
- Can permissions be scoped by reviewer discipline without duplicating files into separate folders
- How does the platform handle large technical files, and is there a per-file size ceiling
- Does search read inside documents, which matters across thousands of scanned title records
- Does the audit trail export, and how long is it retained after a deal closes
- Can access be revoked after download, for when a bidder withdraws holding reserve data
The last one is worth pressing on. Energy diligence hands competitors a detailed view of your acreage and economics, and several bidders in any process will not proceed.
| Worth Knowing
Canadian upstream M&A approached $20 billion in 2025, driven largely by Montney and Duvernay corporate activity, Enverus reports. Cross-border deals add a second regulatory regime and a second set of land recording conventions to an already document-heavy process. |
How CapLinked VDR Supports Transactions For Oil & Gas Industries?
Mapped to the three capabilities above rather than listed as features.
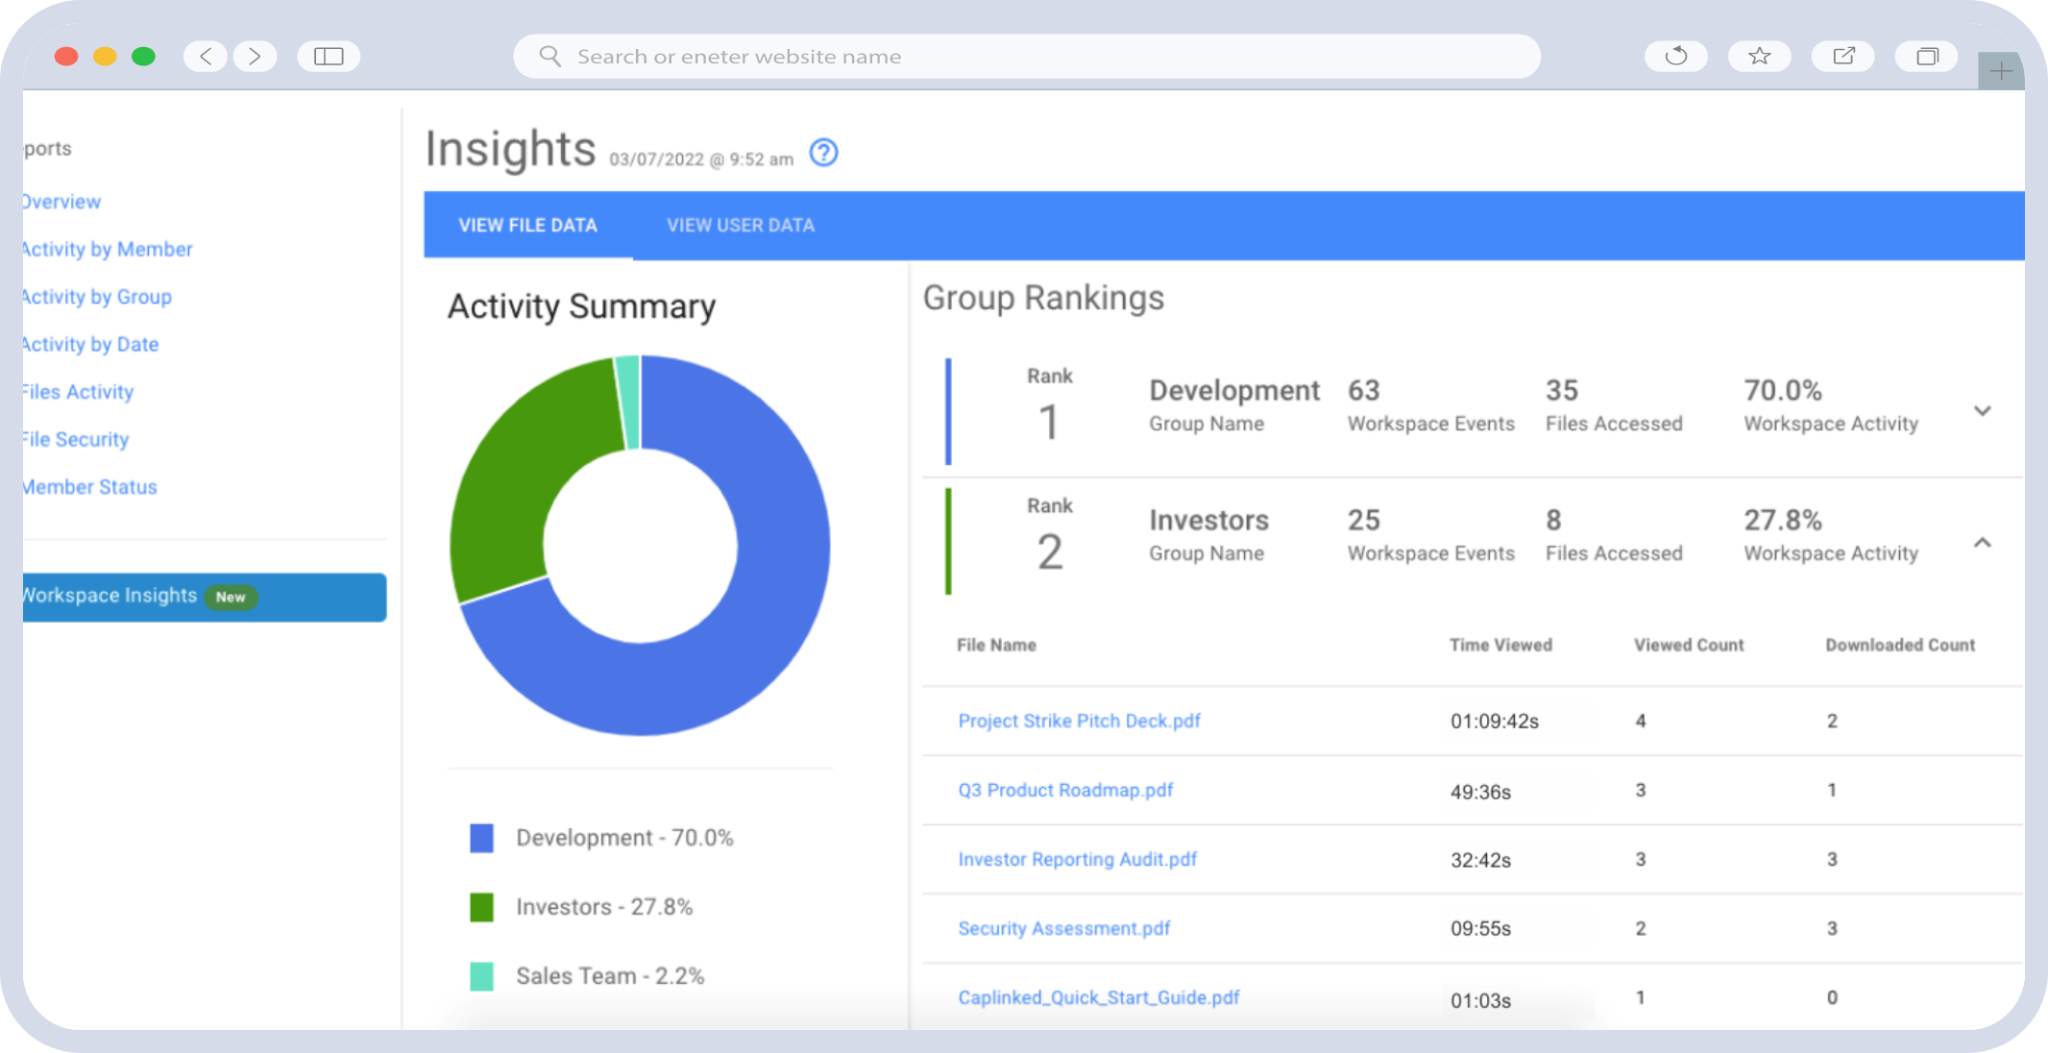
On scoped access, permissions are set per folder with files private by default, so a reserve engineer and an environmental consultant work from the same structure without seeing each other’s material. On the question cycle, EZ Q&A routes each query to the right subject expert and keeps the thread attached to the document. On the record, the audit trail archives every document interaction in a workspace and exports for review.
Regulatory exposure runs deep in this sector, with requirements from multiple agencies and often multiple national governments. Independent assessment covers SOC 2, alongside ISO 27001, PCI SAQ-D and FISMA, and encryption applies 256-bit AES at rest with TLS in transit. The security detail sets out which claim is which, since certified, compliant and assessed are different statements.
Where intellectual property sits inside a deal, whether proprietary seismic interpretation or completion technique, trade secret protection becomes a separate consideration from general document security.
| Running diligence across reserve engineers, land teams, environmental consultants and lenders at once? |
Oil and Gas Due Diligence FAQs
What does oil and gas due diligence cover?
Reserve estimates and the engineering assumptions behind them, title to mineral and leasehold interests, environmental and abandonment liability, and joint operating and marketing contracts. Financial and legal review runs alongside all four.
What is the most common problem found in energy diligence?
Title defects in mineral and leasehold interests. Gaps in the chain of title, unreleased liens and expired leases are usually curable, but curing them takes time a fixed deal timeline may not allow.
Why do reserve reports need verification?
Reserve estimates are engineering judgments rather than measurements. Buyers examine decline curves, recovery factors, the price deck used, and how much of the total sits in proved undeveloped reserves requiring future capital.
Who is liable for well plugging and abandonment after a sale?
Those obligations generally transfer with the asset, along with contamination liability that may predate the seller. Idle wells carry full retirement cost while producing nothing, so they warrant specific review.
How large is oil and gas M&A right now?
US upstream deal value reached $65 billion in 2025 and $38 billion in the first quarter of 2026, the strongest quarter in two years. Only eight deals exceeded $100 million in that quarter.
Why does energy diligence generate so many documents?
A single producing property carries leases, division orders, title opinions, regulatory filings, production records and operating agreements. Across hundreds of wells in several counties, the volume becomes the constraint on timeline.
What should an energy data room be organized around?
Reviewer discipline rather than document type. Reserve engineers, land teams, environmental consultants and lenders each need a different slice, and scoping access by role prevents both over-disclosure and bottlenecks.