Key Takeaways:
- Deal flow is the pipeline of opportunities a firm evaluates. It describes both the rate and the quality of what arrives.
- Deal flow management is what you do with that pipeline. Sourcing fills it; management decides what moves and what dies.
- The deal flow pipeline runs through six stages, from sourcing to post-investment monitoring, and each stage should end with a defined handoff.
- More deals is not the goal. Better conversion is, and the two often pull against each other.
- Four metrics tell you most of what you need: volume, stage conversion, time in stage, and win rate.
- Spreadsheets tend to break down once several deals run at the same time, when version conflicts and duplicate outreach start.
- Many firms run two tools, a pipeline tracker and a data room, and the handoff between them is where time is often lost.
Table of Contents
ToggleDeal flow management is the structured process of tracking, evaluating and prioritizing potential investments or acquisitions as they move from first contact to close. Deal flow is the pipeline itself. Management decides what advances, what stops and how fast, using written criteria, stage gates, metrics and the tools that hold them together.
The distinction between the pipeline and its management matters because the two get solved differently. A thin pipeline is a sourcing problem. A full pipeline that produces nothing is a management problem, and the second is harder to spot.
Conditions have made this sharper. Bain’s Global Private Equity Report 2026 sums up the shift as “12 is the new 5”: a typical deal that needed about 5% annual EBITDA growth to reach a 2.5x return in the 2010s now needs around 10% to 12%. With lower leverage and no multiple expansion to lean on, which deals you pick, and what you pay, decides the outcome. Both are set inside the pipeline.
What Is Deal Flow Management?
Deal flow management is the process of qualifying, prioritizing and moving opportunities through a pipeline toward a close. Deal flow is the stream of potential investment or acquisition opportunities a firm evaluates over a given period, and the term covers two things at once: the rate at which opportunities arrive, and the quality of what arrives.
Both halves matter, and firms tend to report only the first. A hundred opportunities that all fail the investment criteria is not strong deal flow. It is a lot of reading.
The concept applies across private equity, corporate development, investment banking and M&A generally. The mechanics differ, and the logic does not: opportunities arrive, get filtered, and either progress or stop.
How is deal flow management different from deal sourcing?
The two terms get used interchangeably, and they are different halves of the same job. Deal sourcing is how opportunities get into the pipeline: outbound outreach, banker relationships, referrals, screening databases. Deal flow management is what happens to them afterwards: qualification, prioritization and throughput.
A firm can be excellent at sourcing and still lose deals to a rival that simply moved faster on the same target, which is a management failure wearing a sourcing costume.
Why Deal Flow Management Matters
Deal flow management decides three things: which deals reach the investment committee, how fast you move on them, and whether you can forecast when capital goes out.
- Decision quality. Consistent criteria applied consistently means the deal that reaches the investment committee got there on merit rather than on whoever championed it loudest.
- Speed. The firm that answers first, diligences fastest, and signs cleanest wins competitive processes. Every handoff that waits for someone to find a file costs a day.
- Forecasting. Stage conversion rates turn a pipeline into a forecast. Without them, capital deployment planning is guesswork dressed as a number.
| Did You Know
Global private equity acquisitions fell 10% in the first half of 2026 compared with the first half of 2025, while aggregate deal value stayed roughly flat. EY-Parthenon describes sponsors as “active but selective” and applying “a higher bar” where underwriting risk has risen. When fewer deals clear, a badly run pipeline costs you a quarter, not just one opportunity. |
What Are the Six Stages of the Deal Flow Pipeline?
A deal flow pipeline moves each opportunity through six stages: sourcing, screening, initial diligence, investment committee and term sheet, confirmatory diligence, and close with monitoring. Each stage should end with a defined handoff, meaning the specific output the next stage needs to start.
1. Sourcing
Opportunities enter through outbound outreach, intermediaries, referrals, or inbound approaches. The output is a named opportunity with enough information to screen.
Handoff: a named opportunity scored against your criteria.
2. Screening and evaluation
Apply the investment criteria: sector, size, stage, geography, business model. Most opportunities should die here, quickly and cheaply. A screen that passes everything is not a screen.
Handoff: a short case for spending real time, usually the first draft of an investment committee memo.
3. Initial due diligence
The first real spend of time. Preliminary commercial and financial review, management conversations, and a view on whether the thesis survives contact with the numbers.
Handoff: an investment committee memo with the open questions listed.
4. Investment committee and term sheet
The opportunity is presented for approval, and an indicative offer or letter of intent follows. Clear decision rights matter more here than anywhere else in the process.
Handoff: an approved offer and a diligence request list.
5. Negotiation and confirmatory diligence
Full due diligence across commercial, financial, legal, tax, and technical workstreams, running in parallel against the exclusivity clock. This is usually the longest stage and the most compressible one. Open the data room before exclusivity starts, not after: a workspace can be stood up in minutes, so there is no reason to lose the first days of the exclusivity window to setup.
Handoff: an open data room, then a signed agreement.
6. Close and post-investment monitoring
Signing, funding, and then the part pipelines tend to forget: tracking what the investment actually does against what was underwritten. That feedback is what improves the screen next time.
Handoff: a monitoring plan with the underwriting assumptions written down.
| Worth Knowing
Buyout-backed companies are now held around seven years at exit, against an average of five to six years from 2010 to 2021, and about 32,000 unsold portfolio companies worth $3.8 trillion sit in PE portfolios. Longer holds make stage 6 a long job, and the monitoring record is what you will rely on when the exit process opens. Source: Bain & Company, February 2026 |
Figure 1: The six stages of a deal flow pipeline and the handoff each one passes to the next.
| Stage 5 runs on the exclusivity clock. Have the room, the permission groups and the Q&A set up before the letter of intent is signed. |
How Does Deal Flow Management Differ by Firm Type?
The six stages hold everywhere, but who owns the pipeline, what counts as a deal and where it jams depend on the firm.
Private equity
Deal partners and an origination or business development team own the pipeline, and at many firms a deal flow manager or associate keeps the system of record current. A deal is a platform investment or an add-on, and the two usually run as parallel pipelines with different criteria. Investment committee cadence and the pace at which the fund needs to deploy capital drive prioritization. The bottleneck to watch is confirmatory diligence under exclusivity, where a late quality of earnings report or a disorganized seller room eats the clock. For the diligence side in more depth, see due diligence for private equity.
Corporate development
Corp dev runs fewer, more strategic targets, and ideas arrive from business units as often as from bankers. Every target gets weighed against building the capability or partnering first. The bottleneck is internal: aligning the business unit sponsor, finance and legal, and starting integration planning early enough that it shapes the price.
Investment banking
A banker manages two pipelines at once: mandates being pitched, and the buyers inside each live process. Once a sell-side process opens, the bottleneck moves to bidder engagement and Q&A volume, since several parties are asking overlapping questions against the same deadline.
Sector pipelines add their own variables. Pharma and biotech business development teams track licensing and co-development deals alongside M&A, usually under tighter IP controls (life sciences data rooms cover that side). Cybersecurity and other technology-focused funds run thesis-driven pipelines, where the thesis sets the screen. Venture firms manage deal flow too, at much higher volume and earlier stages, which changes the tooling question.
What Are the Best Practices for Managing Deal Flow?
The practices that matter most are written criteria, consistent scoring, stage exit criteria and one system of record. The rest keep the pipeline clean enough for those four to work.
- Write down the investment criteria. Sector, size, stage, geography, and the disqualifiers. Unwritten criteria get reinterpreted deal by deal.
- Score consistently. A simple weighted scorecard forces comparison that narrative does not.
- Prioritize quality over volume. Filtering early and often prevents the deal fatigue that makes teams sloppy on the opportunity that actually mattered.
- Standardize screening and diligence, and reuse the structure. Reusable checklists and request lists, a standard data room folder index, saved invitation messages and permission groups set up the same way each time mean every deal starts from the last one rather than from scratch.
- Set stage exit criteria. A deal advances because it met a defined bar, not because nobody objected.
- Prune on a schedule. Anything static for ninety days gets reactivated with a specific next action or moved to dormant.
- Keep one system of record. A pipeline split across a CRM, a spreadsheet, and three inboxes is not a pipeline.
- Collaborate across functions. Sourcing, diligence, and legal working from the same view stops the duplicated work that eats junior time.
Filling the pipeline is a separate job. Targeted outbound, intermediary relationships and a narrow, clearly stated thesis feed the top of the funnel, and the deal sourcing guide linked above covers each of them.
How Do You Track Deal Flow?
Track deal flow with four metrics read together: deal volume, stage conversion rate, time in stage and win rate. Each one means something specific when it moves.
Table 1: The four deal flow metrics and what a change in each one tells you.
| Metric | What it measures | What it tells you when it moves |
|---|---|---|
| Deal volume | Opportunities entering the pipeline per period | Rising volume with flat closes means the screen is too loose or sourcing is off-thesis |
| Stage conversion rate | Percentage advancing from each stage to the next | A sharp drop at one stage localizes the problem. Heavy loss at screening often means off-thesis sourcing, not good screening |
| Time in stage | Days an opportunity sits at each stage | The bottleneck is wherever this is longest. Often that is diligence, and often the administrative half of it |
| Win rate | Percentage of pursued deals actually closed | Falling win rate against consistent volume means you are competing for the wrong deals, or moving too slowly on the right ones |
Track them together or they mislead. Volume alone rewards noise. Win rate alone rewards only chasing certainties.
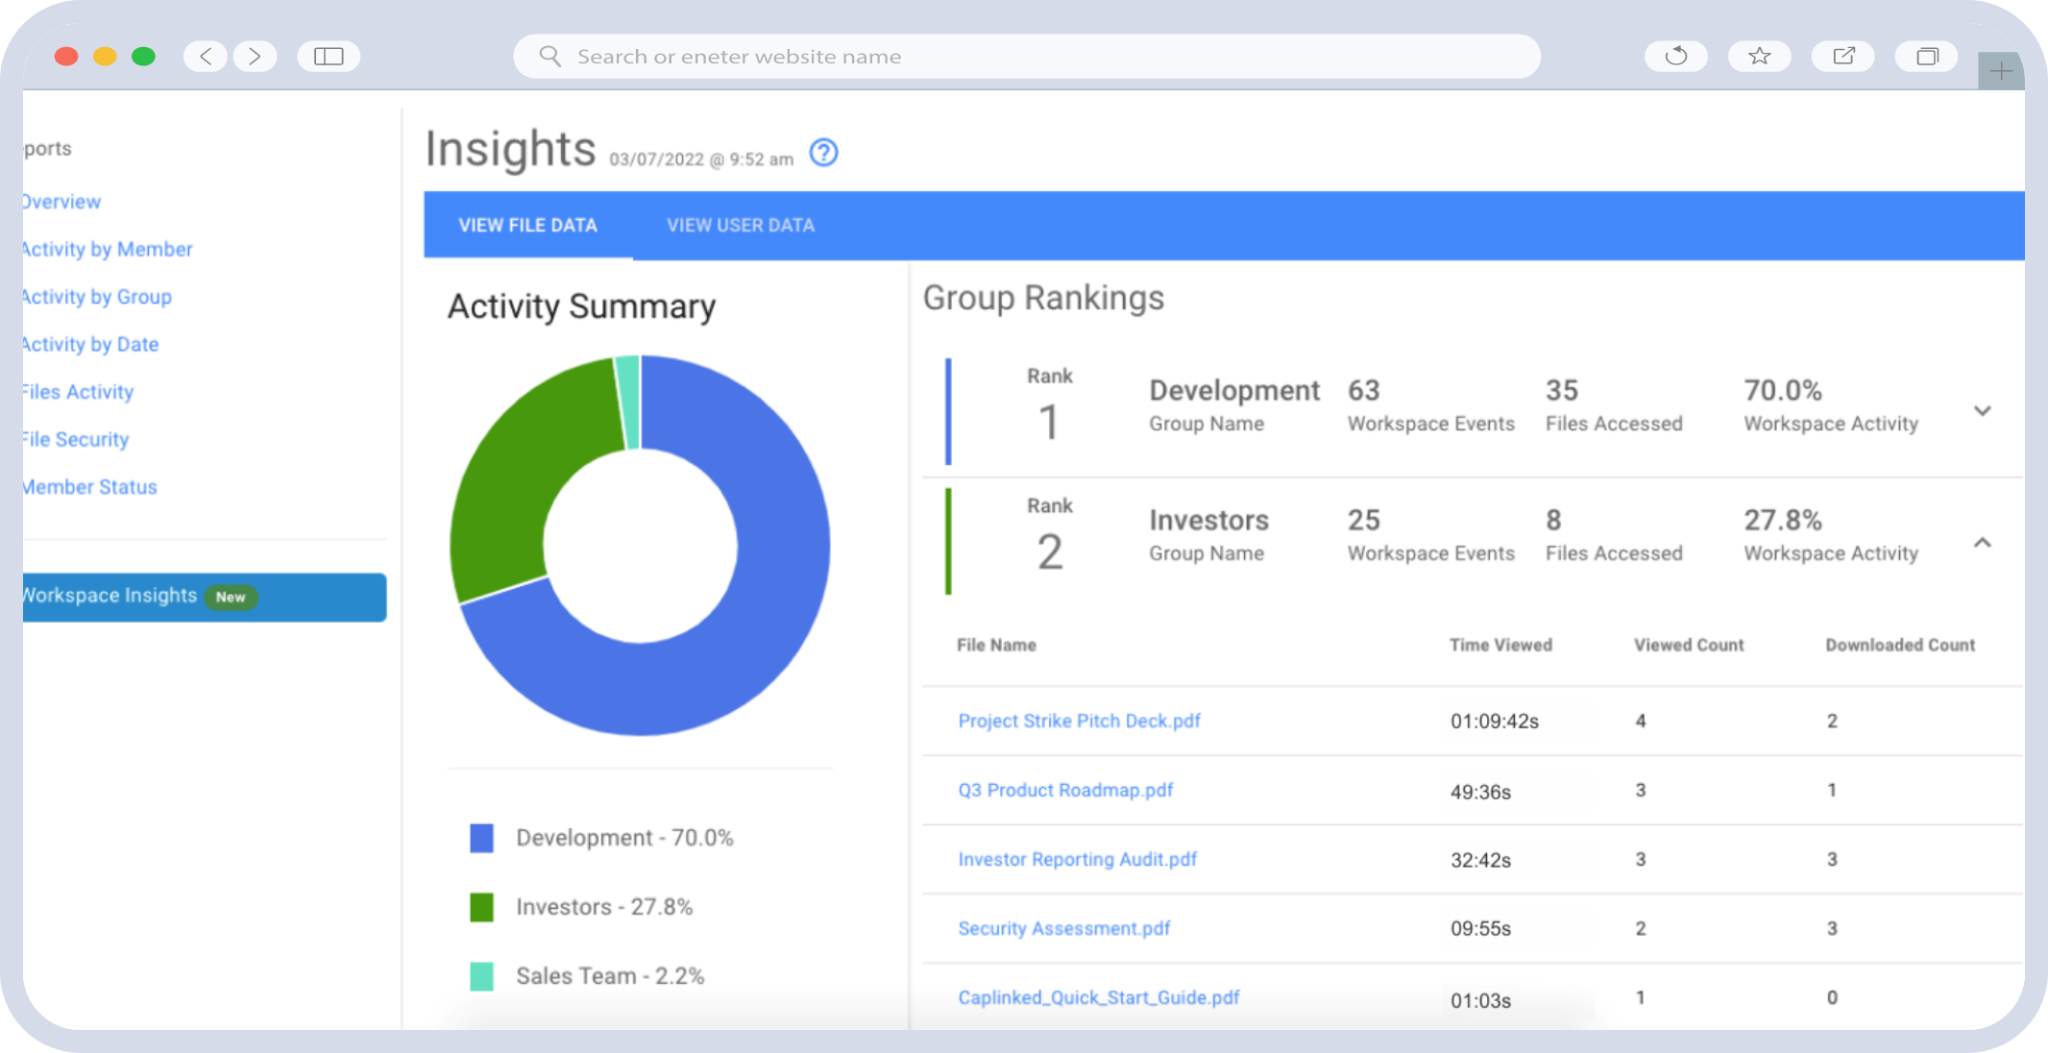
Once a deal is live, the data room adds a layer the CRM cannot see: which counterparties opened which documents, and for how long. That shows attention, not intent, but read alongside the open Q&A list helps you judge whether a process is on schedule and where follow-up will matter.
How Do You Evaluate Deal Flow Management Software?
Evaluate deal flow management software against the bottleneck you actually have, then score a shortlist on the same weighted criteria. The category covers two distinct jobs, tracking the pipeline and running the live deal, and firms often need both without realizing they are separate purchases.
Table 2: The two jobs deal flow software covers, and what to look for in each.
| The job | What handles it | What to look for |
|---|---|---|
| Tracking the pipeline | Deal flow CRM or relationship intelligence platform | Custom stages matching your process, custom fields, automated follow-ups, integrations with email and market data, a single dashboard across concurrent deals |
| Running the deal once it is live | Secure data room | Granular permissions, threaded Q&A, audit trails, document version control, controls that persist after download |
The handoff between them is where time is often lost. A deal progresses from a tracked opportunity to an active process, and the material moves from notes and emails into a controlled environment shared with outside parties. If that transition means rebuilding a folder structure and a contact list from scratch every time, the tooling is not doing the second half of its job.
Buy for the bottleneck you have
Diagnose before you shortlist. If deals stall because nobody knows what stage anything is at, or two people call the same target in one week, the gap is pipeline tracking, and a deal flow CRM fixes it. If deals stall after the letter of intent because diligence drags, requests get answered twice and nobody can say which bidder read the financials, the gap is the data room. If both are true, give the handoff criterion in the template below extra weight.
A scoring template for deal flow platforms
Score each tool from 1 to 5 on every criterion, multiply by the weight, and add the results; a perfect score is 500. The weights below are a vendor-neutral starting point that adds to 100. Move points toward your bottleneck: a bank running several sell-side processes at once might shift weight from stage customization to Q&A and engagement reporting.
Table 3: A weighted scoring template for evaluating deal flow management platforms.
| Criterion | Weight | What “good” looks like |
|---|---|---|
| Stage and field customization | 15% | Stages and fields match your process without workarounds; changes don’t need the vendor |
| Single dashboard across concurrent deals | 10% | Every live deal visible from one login, with status at a glance |
| CRM, email and contact integration | 10% | Contacts and correspondence flow in without re-keying; existing CRM data imports |
| Permissions and security attestations | 15% | Group-level permissions, enforceable two-factor authentication, current SOC 2 Type II report |
| Diligence handoff | 15% | A data room opens from a standard folder index, with contacts and permission groups set up, without rebuilding by hand |
| Q&A and audit trail | 10% | Questions routed to named owners, one answer shared across groups, exportable records |
| Reporting and engagement analytics | 10% | Stage conversion and time-in-stage reports, plus document-level engagement once a deal is live |
| Adoption by external parties | 10% | Counterparties work in a browser with no plug-in, and need little or no training |
| Support and onboarding | 5% | Named support contact, setup help for the first deal, clear response times |
| Total | 100% | Maximum weighted score: 500 |
Can one platform handle pipeline tracking and secure document sharing?
Yes, some platforms combine a pipeline view with a data room, and many firms instead pair a deal flow CRM with a separate data room. Either approach works. The deciding factor is the handoff: when a tracked opportunity becomes a live process, can you open a room with the right folder index, contacts and permission groups without rebuilding them? Test that during a trial with a real deal’s structure rather than a demo workspace.
How CapLinked Supports Deal Flow for PE, Corp Dev and Bankers
CapLinked is not a deal flow CRM competing with dedicated pipeline platforms. It is where the pipeline goes once a deal becomes real: the workspace for secure document sharing during diligence, with the tracking that surrounds a live process.
Every workspace sits on one dashboard, so concurrent deals run from one login, and workspaces stay open across transactions rather than closing at deal end. Contacts come in through a Salesforce connection or a CSV file, and Tasks lets administrators assign document requests to colleagues or workspace members with a description and a priority.
For private equity teams
Spin up a workspace per target from the same structure: drag in your standard folder index and it numbers itself, apply rights across every folder in one action, and reuse saved invitation messages. Where enabled for a group, AI Document Summary condenses a document in roughly 30 to 60 seconds and can flag contradictory figures in target materials. Activity Tracker shows which documents each reviewer on the deal team has opened, so coverage gaps show up before the investment committee meeting.
For corporate development teams
Concurrent targets sit on one dashboard, and white labeling, standard on all plans, puts your own branding on each room. Tasks keeps internal and external document requests assigned, and non-administrator editing lets an outside party complete a form or document inside the room instead of emailing it back.
For investment bankers
Give each bidder its own permission group, with Q&A visibility set per group so bidders don’t see each other’s questions. Activity Tracker compares groups by logins, views, downloads and review time, which lets you rank bidders by engagement and sequence follow-up, though it measures attention rather than intent. EZ Q&A routes each question to a named administrator, and the administrator-only AI Executive Report turns room activity into a PDF status update for the client. More on data rooms in investment banking.
CapLinked’s virtual data room holds SOC 2 / SSAE 18 Type II attestation and encrypts data with 256-bit encryption at rest and in transit. Professionals in more than 75 countries use the platform, including teams at 45 percent of Fortune 1000 companies.
| A pipeline is only as good as what happens when a deal gets real. Run your next live deal in a workspace; the free trial runs 14 days. |
Deal Flow Management FAQ
What is deal flow management?
The structured process of tracking, evaluating, and prioritizing opportunities as they move toward a close. Sourcing fills the pipeline; management decides what advances, what stops, and how fast.
What is the difference between deal flow and deal sourcing?
Deal sourcing gets opportunities into the pipeline through outreach, referrals, and screening. Deal flow management is everything that happens afterwards: qualification, prioritization, diligence, and close.
How do private equity firms manage deal flow?
PE firms write down investment criteria, score every opportunity the same way, run platform and add-on pipelines in parallel, set stage exit criteria tied to investment committee cadence, and keep one system of record from sourcing to monitoring.
What does deal flow management software do?
Pipeline platforms track opportunities through custom stages, centralize notes and contacts, automate follow-ups, and report on conversion. A secure data room handles the separate job of running the deal itself once diligence begins.
How do you evaluate deal flow management software?
Identify your bottleneck first, then score a shortlist on weighted criteria: stage customization, a single dashboard, integrations, permissions and security, the diligence handoff, Q&A and audit trail, reporting, external-party adoption and support.
Can one platform handle pipeline tracking and diligence document sharing?
Some platforms combine both, and many firms pair a deal flow CRM with a separate data room. The deciding factor is whether a live deal’s folder index, contacts and permissions carry over without being rebuilt.
What deal flow metrics should you track?
Deal volume, stage conversion rates, time in stage, and win rate. Together they show whether the problem is sourcing quality, a specific stage bottleneck, or competitive positioning. Individually, each one misleads.